Thursday, October 31, 2013


Halloween or Hallowe'en (a contraction of "All Hallows' Evening"), also known as All Hallows' Eve, is a yearly celebration observed in a number of countries on October 31.

It is the eve of the Western Christian feast of All Hallows or All Saints Day. 

According to many scholars it was originally influenced by western European harvest festivals and festivals of the dead with possible pagan roots, particularly the Celtic Samhain.

Others maintain that it originated independently of Samhain and has Christian roots.

North American almanacs of the late 18th and early 19th century give no indication that Hallowe'en was celebrated there.

The Puritans of New England maintained strong opposition to Hallowe'en and it was not until the mass Irish and Scottish immigration during the 19th century that it was brought to North America in earnest.

Confined to the immigrant communities during the mid-19th century, it was gradually assimilated into mainstream society and by the first decade of the 20th century it was being celebrated coast to coast by people of all social, racial and religious backgrounds.

Typical festive Halloween activities include trick-or-treating (also known as "guising"), attending costume parties, carving pumpkins into jack-o'-lanterns, lighting bonfires, apple bobbing, visiting haunted attractions, playing pranks, telling scary stories, and watching horror films.

How so ever you choose to mark the day, to each and all... a safe and happy night.


==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Wednesday, October 23, 2013

Canso Investment Counsel President John Carswell discusses the Canadian housing bubble


Canso Investment Counsel President John Carswell discusses the the prospect of a Canadian housing bubble and its effects on the marketplace:
Mike: John you've had very strong view with the U.S. housing crisis and subprime mortgage lending. Maybe you could update us with your views now on the Canadian market.

John: Well Mike if you look at the United States situation you had a lot of signs in their marketplace that their housing market was overvalued. At the same time the Canadian housing market was overvalued by similar measures.

But when the Americans had their subprime mortgage meltdown, people bought houses they couldn't afford through securitization, the music stopped, and there was no money available so the housing market crashed.

If you look through history there has never been a soft landing in a real estate market. Normally people buy, and they buy, and they buy, and there is leverage involved. So when you have speculators that have borrowed money for rising asset prices, that's not good.

If in Canada all of the houses and condos that we have constructed were owned by people that were going to live in them; we estimate prices should fall thirty to forty percent to make them affordable for people. Even at that there is probably not enough people to buy the houses.

The problem now becomes all these foreign investors who have been buying condos and houses. Are they coming to Canada because they want to become Canadian and live with us? No. They're trying to get money out of their home country because of political turmoil. Iranian, Russians, and Chinese who fear regime change are buying six hundred square foot condos as an investment.

Well the cash yield on condos now in the Toronto market is about two percent. If you buy a condo for six hundred dollars you will get something in the vicinity of twelve thousand dollars a year. That's one thousand dollars a month and that's not very good for your investment health.

So what we think is going to happen is people say you need a catalyst, rising rate or unemployment. Well you never know what the catalyst is going to be until afterwards, but if houses were overvalued by fifty percent, and the people who live in them can't afford their own houses, why should the prices be that high?

What we think is going to happen here is the housing market is going to settle back at some point. And what does that mean? Well, thirty percent of our economy is based on housing. If you look at GDP, gross domestic product, the value of all goods and services in the economy, Canada and the United States were both spending three to four percent.

During the credit bubble from 2002 to 2007 we went up to six-seven percent. The Americans have dropped back down to two to three percent, while we've increased. So the problem now becomes 'do we need all these houses'? Well, I'd suggest to people living in a four thousand square foot house, because they got the biggest mortgage and the biggest house as an investment, that they might have trouble selling it if there is not someone else who wants to have an investment.

So how does it happen and when does it happen? We don't know. But one of the reasons we have such a low weight in Canadian financial stocks, and people exposed to Canadian consumers, is that if you have the most levered consumers in the world, and they borrowed the most and have the least ability to service their debt, at some point things won't work out for them.
Almost sounds too logical, doesn't it? Particularly given the statistics from our last post.

But in the frenzy of a bubble, logic is always in short supply.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Monday, October 21, 2013

In these two sets of numbers lie Canada's housing bubble.


There's an article in today's Vancouver Sun by Barbara Yaffe.

The Canadian Association of Accredited Mortgage Professionals estimates, homeowners in this country — of whom 60 per cent carry mortgages — owed nearly $1.2 trillion in mortgage debt last year, up from $664 billion in 2008. In other words, national mortgage debt has nearly doubled in just four years.
Combine that with the fact that CMHC has gone from $100 Billion in insured mortgages in 2006 to almost $600 Billion today and you know where Canadians got the money to bid the price of real estate to astronomical levels.

Debt fuelled our bubble, plain and simple.

Throw in emergency level interest rates to facilitate the low monthly payments on massive mortgage amounts and you get a real sense of why the bubble has continued for so long.

But make no mistake.  These are not real estate prices which reflect intrinsic value.  The real estate bubble is born of excess credit.  Massive, excess credit.

This is a scenario that has been repeated over and over the past 500 years.
A boom caused by excess credit will always bust. Ours will be no different.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Saturday, October 19, 2013

Are you ready for Laneway House tours?


The Laneway house concept was launched in 2009 and Vancouver recently passed the 1,000 Laneway house permit mark.

On October 19th, 2013 the Vancouver Heritage Foundation is holding a Laneway House Tour.

That's right... we've now reached the truly sublime as the archaic is raised aloft.

The tour will take you to seven laneway homes, runs for approximately four hours, and can accommodate up to 500 people. Tickets are $30.

Incredibly this is the 2nd tour offered this year.  Supposedly the first one on June 2nd, 2013 was so successful this reprise tour has been scheduled rather than wait for Laneway House Tour 2014.


Presumably a mortgage broker will be on hand to perform sleight of hand and facilitate your technically illegal , zero down, CMHC insured, million dollar mortgage application.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Friday, October 18, 2013

The View from Richmond - James Wong's monthly real estate update


Richmond real estate agent James Wong is out with his mid October report on the end of September sales data.
Richmond’s housing market is stabilizing.

Richmond experienced one of the highest run-up in home prices the past 10 years. The fear of a impending collapse in home prices in 2013 did not happen. The built up in the supply of homes in the second half of 2012 slowed down through 2013, aided by improved sales since March, 2013. The MOIs for detached homes, townhomes and condos are now at more balanced levels.

The double digits MOIs for detached homes, townhomes and condos a year ago declined gradually to around 7, 5 and 6 respectively towards the end of September, 2013.

What to expect of 2014?

The 5-year mortgage rate jumped moderately and currently it is about 0,5% higher than 6 months ago. Home prices in Richmond managed to hold at current level after suffering from around 12% drop in values compared to their peaks around the middle of 2011.

When home ownership is reported to be at the 70% level, and average annual household income just over $60,000, the demand for homes are depending on interest rates remaining low for extended period of time. The housing market is fragile. At current price levels, any further spike up in interest rates would defer many first time and move-up buyers from buying.
==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Thursday, October 17, 2013

In honour of the Debt Ceiling extension, an interesting video by Mike Maloney on the US Federal Reserve


The debt ceiling debate in the United States is over (for a few months, at least) and to we take the opportunity to hilight this video from Mike Maloney discussing the debt based money system and the current version of US Currency: the Federal Reserve note.

We say 'current version' because the United States has gone through a number of different currency's in it's 237 year history.

The current version, the Federal Reserve note, is only 99 years old.

So as the US debt ceiling is raised once again, we bring you this interesting dissertation on the fiat the currently makes up the world's reserve currency.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Wednesday, October 16, 2013

Wed Post #2:Typhoon Wipha hits Japan; catastrophe avoided at Fukushima


Following up on yesterday's post about a 'once-in-a-decade' Typhoon hitting Japan and the threat it posed to the Tsunami-ravaged Fukushima nuclear power plant, it appears the storm has now passed.

Good news for both Japan and the Village on the Edge of the Rainforest which would be impacted by any radiation spewing into the atmosphere.

TyphoonWipha has killed 17 people so far and more than 50 are missing. Izu Oshima, an island south of Tokyo was worst hit, suffering landslides and flooding. During the height of the storm, more than 500 flights at Tokyo's Haneda and Narita airports were cancelled, and thousands of schools closed. About 20,000 people were told to leave their homes because of the danger of flooding . Typhoon Wipha was the worst storm to hit the region since October 2004.
In a follow up article from The Guardian: Typhoon Wipha wreaks deadly destruction on Japan
A typhoon has killed 17 people in Japan, but largely spared the capital and brushed by the wrecked Fukushima nuclear power station.

More than 50 people were missing after typhoon Wipha roared up Japan's east coast, including two schoolboys engulfed by waves on a beach; 20 more were hurt by falls or being struck by flying debris. About 20,000 people were told to leave their homes because of the danger of flooding and hundreds of flights were cancelled.

Sixteen people were killed on Izu Oshima island, about 75 miles (120km) south of Tokyo, as rivers burst their banks. The storm set off mudslides along a mile-long stretch of mountains.

Wipha sustained winds of 78mph (126km/h) with gusts up to 180km/h.

The storm brought hurricane-force winds and torrential rain to the Tokyo metropolitan area of 30 million people at the peak of the morning rush-hour.

The operator of the Fukushima nuclear plant, Tokyo Electric Power Corp, cancelled all offshore work and secured machinery as the storm approached.

The operator, known as Tepco, has been struggling to contain radioactive leaks since a 2011 earthquake and tsunami caused extensive damage and triggered the world's worst nuclear crisis since Chernobyl in 1986.

A Tepco spokesman said Typhoon Wipha had caused no new problems at the plant, which is on the coast 130 miles (220km) north of Tokyo.

The storm dumped heavy rain that had to be pumped out of protective containers at the base of about 1,000 tanks storing radioactive water, the byproduct of a jerry-rigged cooling system designed to control wrecked reactors.

The rainwater was checked for radioactivity and released into the sea, the company spokesman said.

Wipha has been down-graded to a tropical depression.
The photo above shows a man walking near collapsed houses following a landslide caused by Typhoon Wipha on Izu Oshima island, south of Tokyo.

From The Japan Times:
Typhoon Wipha brought strong winds and heavy rain to the Tokyo metropolitan area early Wednesday, shutting down large portions of the region’s transportation network.

On Izu Oshima Island in the Pacific about 120 km south of Tokyo, at least 13 bodies were found and around 20 people were missing after several houses collapsed amid record rainfall of 122.5 mm per hour, according to local authorities and police.

In Machida, Tokyo, a woman believed to be in her 40s died after being swept away by a swollen river, police said.

Air travel was heavily disrupted. Japan Airlines grounded 189 domestic flights while All Nippon Airways scrapped 211 domestic and international flights.

Tokyo Electric Power Co. said it took steps to deal with water inside barriers around tanks storing radioactive water at the Fukushima No. 1 nuclear plant.

Tepco has set tentative limits on radioactive materials in water around the tanks and will release water inside their barriers if radiation levels are below those ceilings. The ceilings are 25 becquerels per liter for cesium-137, 15 becquerels for cesium-134 and 10 becquerels for strontium-90.

All of the ceilings are one-third of the legal thresholds for the release of water into the sea.

At the tank areas where high radioactivity levels were detected, water near the tanks will be transferred to a newly build 4,000-ton makeshift tank.
With the storm now heading towards Alaska it appears further catastrophe, thankfully, has been avoided for now.


Below is some raw footage from Japan:


==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Wed Post #1: Inventory Tracker Stats


A number of you have been asking about the Inventory Tracker stats on the sideboard.  The blogger widget has not been functioning for the past few months so we've been unable to make updates.

Today we were successfully able to delete the widget and re-enter the monthly totals.  Regular daily entries will resume starting in November.

Speaking of stats, below is a screenshot from VCI of Ham Solo's latest foreclosure statistics for you (click to enlarge):


==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Tuesday, October 15, 2013

From bad to worse: Once-in-a-decade Typhoon threatens Japan's Fukushima nuclear power plant


For those who follow the VW twitter feed, you know that one faithful reader (@Travel_Uruguay) has been a keen follower of the developments around the Fukushima nuclear power plant since the devastating earthquake/Tsunami of March 11, 2011.

Last week a tweet was received from TU regarding an article on the website ENENEWS, which headlined: Pro-Nuclear Expert: Typhoon collapsing Fukushima fuel pool “a very real concern — I don’t know what it is they’re doing about that”


Japan is currently being assaulted by Typhoon Wipha which is moving across the Pacific straight towards the capital, Tokyo, and is expected to make landfall during the morning rush hour bringing hurricane-force winds to the metropolitan area of 30 million people.

The center of the storm was 860 km (535 miles) southwest of Tokyo at 0800 GMT, the Japan Meteorological Agency said on its website. It was moving north-northeast at 35 kph (22 mph).

The storm had weakened as it headed north over the sea but was still packing sustained winds of about 140 kph (87 mph) with gusts as high as 194 kph (120 mph), the agency said.

The agency issued warnings for Tokyo of heavy rain, flooding and gales, and advised people to be prepared to leave their homes quickly and to avoid unnecessary travel.

A spokesman for the meteorological agency said the storm was a "once in a decade event".

The typhoon is expected to sweep through northern Japan after making landfall and to pass near the crippled Fukushima nuclear power plant, on the coast 220 km (130 miles) northeast of Tokyo, later on Wednesday.

Typhoon Wipha is the strongest storm to approach eastern Japan since October 2004. That cyclone triggered floods and landslides that killed almost 100 people, forced thousands from their homes and caused billions of dollars in damage.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Sunday, October 13, 2013

Happy Thanksgiving


Monday is Thanksgiving Day today in Canada and Columbus Day for our American cousins.

A lot of people wonder why Thanksgiving Day in Canada is celebrated so much earlier than in the United States.

The first Thanksgiving Day after Canadian Confederation was observed as a civic holiday on April 5, 1872, to celebrate the recovery of the Prince of Wales (later King Edward VII) from a serious illness.

Starting in 1879 Thanksgiving Day was observed every year, but the date was initially a Thursday in November. 

The date of celebration changed several times until, in 1957, it was officially declared to be the second Monday in October. 

The theme of the Thanksgiving holiday also changed each year to reflect an important event to be thankful for. In its early years it was for an abundant harvest and occasionally for a special anniversary.

After World War I, an amendment to the Armistice Day Act established that Armistice Day and Thanksgiving would both be celebrated on the Monday of the week in which November 11 occurred, starting in 1921.

Ten years later, in 1931, the two days became separate holidays, and Armistice Day was renamed Remembrance Day. From 1931 to 1957, the date was set by proclamation, generally falling on the second Monday in October, except for 1935, when it was moved due to a general election.

In 1957, Thanksgiving was permanently set to be the second Monday in October.

Happy Thanksgiving Day to all and all the best to each and every one who stops by the blog today.

if you're reading this Sunday night, remember to set the scale back 10lbs before bed ;-)

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Thursday, October 10, 2013

Vancouver's foreclosure rate running at 6 per day in October 2013


As mentioned in the last post, Ham Solo has been posting daily foreclosure data on cases filed in BC over on the blog Vancouver Condo Info.

As of October 10th, there have been 48 foreclosures in the City of Vancouver.

That's a rate of 6 per business day at a time when record setting cheap interest rates are supposed to help people pay off their debts.

It speaks volumes.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.


Wednesday, October 9, 2013

Pre-sales closing crunch in Toronto? And... Vancouver foreclosures running at 6-7 per working day.


Debt is endemic. They use lines of credit to make mortgage payments. They routinely increase the size of their home loans to renovate. Four in ten people now say they have trouble paying their monthly bills. And yet 70% own a house. Prices have been bloated by cheap money, not greater income.
That's a quote from one of Garth Turner's posts (May 16th, 2013)

Mortgage brokers, realtors and developers have seen a surge the last few months in people who bought pre-construction condos two to three years ago “scrambling” to get financing to close deals. 
Some have had to walk away from deposits worth tens of thousands of dollars. Others have been forced to borrow from family — or against their principal residence — to come up with final payments on condos that lenders are no longer keen to finance, according to interviews with a number of players in Toronto’s condo industry. 
Hardest hit have been the self-employed who had pre-approvals from lenders when they bought their pre-construction units. But now, with the unit almost complete and final payments due, they are being told they need 35 to 50 per cent down, instead of just 20 per cent of the purchase price, unless they want to rely on secondary lenders offering rates that can hit double digits. 
Many investors who bought units intending to flip them on completion, or rent them out for a few years, have also been shocked to find they thought they had pre-approvals, but they are no longer being honoured in the wake of tighter lending rules imposed by Ottawa.
Can you imagine what things will be like if the Federal Government responds to the idea that mortgage debt is a threat to the economy?

Or if interest rates really do start to rise?

On another note, an interesting post over on Vancouver Condo Info from Ham Solo


From the start of the last paragraph: "Looking at a couple of weeks of data, adjusting for double-counting, we are seeing Vancouver foreclosures totalling about 6-7 per working day."

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Tuesday, October 8, 2013

FP: Mortgage debt putting our national economy at risk.


Interesting article in the Financial Post yesterday. Titled Stephen Harper told mounting mortgage debt is putting ‘our national economy at risk’, the news article details how the Federation of Canadian Municipalities, made up of member cities representing 90% of the nation’s population, have told the Prime Minister that the high cost of housing was the most “urgent” financial issue facing Canadians today.
We have been warned before, and often. The federal government and the Bank of Canada, in particular, have lectured us about the evils of sky-high consumer debt and still-creeping house prices — and the mounting threat to the economy — as rock-bottom interest rates inevitably begin to rise...

Canada Housing and Mortgage Corp., the Crown agency responsible for insuring mortgages to approved buyers, uses a 30% threshold of total household income going to housing. Anything above that, and consumers could end up over their heads.

Dallas Alderson, director of policy and program at the Canadian Housing and Renewal Association, said one-quarter of Canadian are over that limit.
What do they want the Prime Minister to do?
“We believe that as the government sets its priorities for the next two years, it should address the high-cost of housing in Canada, the most urgent bread-and-butter issue facing Canadians today."
Of course when these groups ask the Federal Government to intervene, it usually means more subsidies, which is the type of meddling in the past which has created the mess in the first place.  Remember, greatly increasing CMHC's balance sheet was all about making housing 'affordable'. Notes the FP article...
Finn Poschmann, vice-president of research at the think-tank C.D. Howe Institute, said Ottawa has “little jurisdiction and almost no practical capacity to deliver housing.”

“Past attempts to do so, through CMHC for example, have produced financial disasters for the people who participated and put CMHC in grave financial situation.” he said.

“We wouldn’t want to see that again, nor the federal mortgage agency deeply underwater and as similar U.S. agencies have been, through the course of much more recent financial disasters.”
Curiously no one suggests removing the punch bowl which created the sky-high housing values to begin with.

Yanking that punch bowl away will trigger a very painful process.  But it's the long term solution that is required.

Speaking about the punch bowl of ultra low interest rates, the Globe and Mail notes that GM Canada chief frets over credit-driven car sales.
The president of General Motors of Canada Ltd. is worried that ultra-cheap auto loans could be causing Canadian vehicle sales to spike just as home sales did during the U.S. housing bubble.

Canadians are on pace to drive more than 1.73 million new vehicles off dealers’ lots this year, breaking the record of 1.703 million, but that’s a higher level than economic indicators suggest sales should be, Kevin Williams told The Globe and Mail’s editorial board Monday.


Part of the reason, he noted, includes eight-year, interest-free loans being offered by some auto companies. His comments highlight again the hot-button issue of consumer debt, singled out by Finance Minister Jim Flaherty and the Bank of Canada as a critical concern before the inevitable rise in interest rates.


Mr. Flaherty has focused on mortgage debt, but auto loan debt has been rising in the fierce fight among auto makers for market share and their battles with each other and Canada’s Big Six banks in the auto lending market.

Auto loan debt rose 8.6 per cent in the second quarter from year-earlier levels, outpacing the increase of 6.1 per cent in total debt, according to numbers compiled by Equifax Canada.

Consulting firm J.D. Power and Associates said last month that 64 per cent of Canadians who finance vehicle purchases are taking on terms of six years or longer.

The longer terms are designed to make monthly payments as low as possible, Mr. Williams said, but they mean in some cases buyers will return to dealers for a new vehicle still owing money on the vehicle they’re trading in.
The unwinding of all of this is going to be very, very painful.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Friday, September 20, 2013

Are you ready for the $1.2 million converted garage as your home?


Yesterday we told you about the upcoming auction of a 526 square foot 'laneway' house in Vancouver.

Laneway houses are one of the 'solutions' for increasing density on the Wet Coast.  Instead of building a garage, use the space for a self-contained rental suite.

But they aren't just being used as mortgage helpers anymore.  As noted in yesterday's post, they are now being marketed as separate properties. The 526 square foot mansion profiled in our last post is 'valued' at $500,000.

And as stunningly stupid as that sounds, how about the $1million + lane way home?

Well it's here.  Above is a new listing (pictures yet to come) for a laneway house at 2330 W. 7th Avenue in Vancouver with an asking price of $1,278,000.  From the listing description:
Welcome to the most desirable coach house in the highligh sought-after Kitsalano neighbourhood. A home that instantly feels right. Lots of private outdoor space, open concept layout, hardwood floors throughout, in-floor radiant heating,vaulted ceilings, built-in speakers and designer series Viking appliances are just some of the many features in this home. Architecture by Alexander Ravkov Inc, Interior and Design and Construction by Open Concept Development. Full 2-5-10 New Home Warranty. Elevate your lifestyle with this magnificent new home!
We'll update with pictures when they become available.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Thursday, September 19, 2013

How expensive is Vancouver? Converted Garage's now being auctioned off as detached homes


Laneway houses. The latest fad where, instead of building a garage, developers are allowed to construct a small 'laneway' house.

Usually these creations are considered a 'revenue generator', a secondary suite.

But how about buying the laneway shack outright as your primary house?

Up for auction will be this 516 square foot - yes a house smaller than some living rooms - laneway house. This tiny house will be auctioned off live at the Interior Design Show West (IDS West) at the Vancouver Convention Centre on Sept. 21. There is no minimum bid, but the house is valued at $500,000. All proceeds from the sale will support the Alzheimer's Society of B.C.

Marevelous.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Wednesday, September 18, 2013

News item - BC NDP leader Adrian Dix resigns


Hat tip: Saj Karsan

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Tuesday, September 17, 2013

How to be a Vancouverite


Too many things bang-on in this humorous clip.

Hat tip: Ben Rabidoux

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Monday, September 16, 2013

Another case of 'Newsvertising', this time in the National Post


On the weekend we shared with you the cover of the Financial Post Magazine (pictured above).

It appeared on September 3rd, 2013 in the National Post newspaper and had a stunning headline: "THE SKY IS NOT FALLING - Why real estate doomsayers continue to be wrong"

Pretty powerful message. Forwarded as friendly 'chiding', it represents the quintessential example of media manipulation in real estate today. To the average person, this article appears to be a 'news story'. 

But as one of our faithful readers noticed in the comments section of yesterdays blog post, it's not a news article - it's an adverting feature; an advertisement dressed up to look like a news story.

Online, the article is contained in the "Special Sections' of the National Post (click on all images to enlarge):


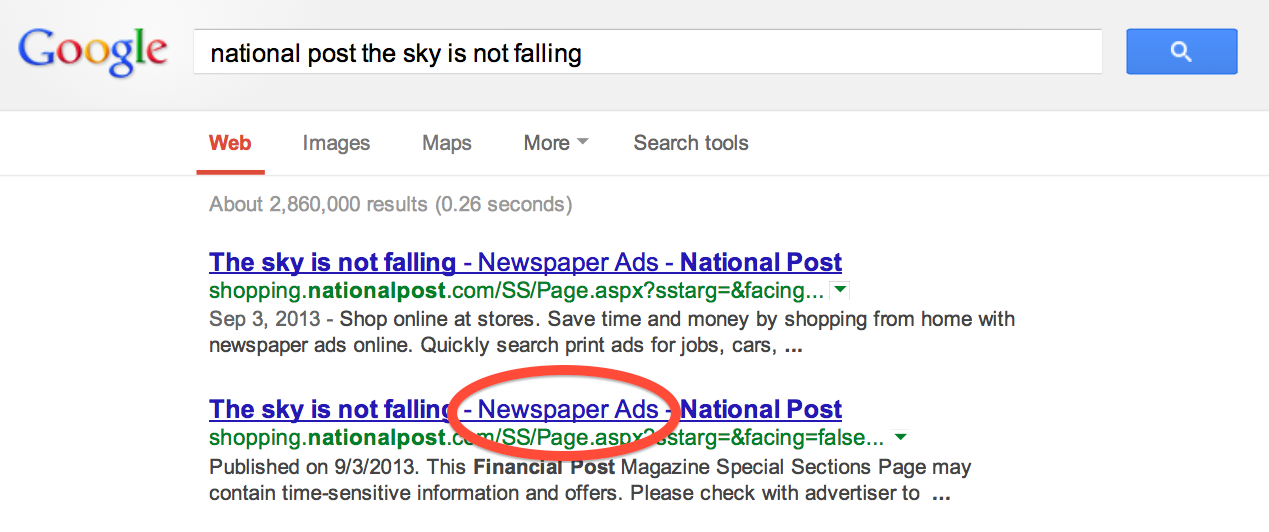
For those who follow this blog regularly, when you see 'Special Sections', the spidey senses start to tingle. Google the article headline and you discover EXACTLY what this article is:


That's right. Google makes it very clear it's not a news article, its a newspaper ad, the content written by a real estate shill who paid to have it inserted in the paper.

Faithful readers will recall we covered a similar misleading article in the Vancouver Province back on March 26, 2013 and discussed it again here.

Desperate for advertising dollars, the mainstream media is increasingly willing to take paid advertisements and present them as actual news stories with little or no indication that what you are reading isn't real news.

Naturally the real estate industry will pay handsomely for the chance to mold public opinion under the guise of legitimate news. Who wouldn't when you dealing with an industry where Billions of dollars are spent based on 'consumer confidence'?

But when the print media sells it's journalistic integrity like this, is it all that surprising that they have become an unsustainable proposition?

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Friday, September 13, 2013

A Minsky Moment precursor?


The Financial Post front page says: "THE SKY IS NOT FALLING: why the real estate doomsayers continue to be wrong."

Full story here.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Monday, September 9, 2013

Globe and Mail on the Condo Market: Lots of supply, low demand, prices softening.


In case you missed it, there was an article in the Globe and Mail on Friday titled, "Vancouver condo buyers take a second look", and the picture it painted was anything but rosy.
Derek Hynes was thinking like a lot of Vancouverites when he purchased his one-bedroom condo in one of Surrey’s new towers. He thought its value would rise each year, enough to make the purchase an investment in his future. He’d build equity until he had enough to purchase a bigger place, maybe even the down payment on a house.
Of course what Hynes is discovering is quite the opposite.  As the G&M notes, the expectation of buyers like Hynes is that that every home should build equity, a hangover from the pre-2008 years, when it seemed that real estate had nowhere to go but up, up, up. Average income earners were purchasing presale units and flipping them by the time they were completed, pocketing $50,000 or so in the process.

But those days are long over and articles like this one in the Globe show that a shift is underway.
As many condo owners who purchased five years ago and are trying to sell today can attest, the equity simply did not materialize. They are often breaking even, or selling for slightly more or less. Today, a condo in Vancouver is no longer viewed as a winning investment, so much as affordable housing and forced savings plan.

And if you consider that mortgage payments are still higher than those in Toronto, condos aren’t even that affordable. A recently released real estate report on Canadian cities says: “Despite the 2012 drop in Vancouver’s median condominium price and a further decline expected in 2013, the area’s affordability is forecast to remain the weakest by far among this report’s eight cities, both this year and throughout the forecast.”
Say it isn't so?

Apparently Hynes, purchased his 620 sq. ft. condo for $182,000 (which was $7,000 below the asking price) and he was recently thinking of selling the unit until he saw that his neighbour on the same floor, with the same suite, has just listed for $179,000.

Talk about a kick in the groin.
“I thought it would at least keep its value, so I’m surprised,” Mr. Hynes says. “If it had kept its value, I definitely would have sold right now.”
Hynes says his work colleagues, friends and relatives are facing the same situation. His cousin just sold her condo after renting it out for five years, and she lost money on it.
“It was for the exact same reason I’m losing out,” Mr. Hynes says. “Because there are so many condos in the area.”
What sellers are discovering, according to the article, is that there are too many new condos. Since the economic slump of 2009, condo starts have been on the rise, and above the 20-year average ratio of starts-to-population growth. Developments were going up almost as if it were 2007 again.
“This left the inventory of completed but unsold apartment condominiums very high by the past decade’s standards,” says the Genworth/Conference Board of Canada report, which provided those numbers.

With the slump in prices, sales have recently picked up. The benchmark price of an apartment decreased 1.1 per cent from August, 2012, to $366,100 in August this year, according to the Real Estate Board of Greater Vancouver. Sales last month went up 40 per cent over August, 2012.

“Even though the real estate market is booming, the prices mostly remain the same,” says Vadim Marusin, who’s the founder of Estateblock.com, a new real estate search engine that maps the Multiple Listing Service listings
Urban Analytics’ Michael Ferreira tracks the market on a quarterly basis, and he sees a condo glut that’s softening prices.
“We’ve seen the unsold inventory of product under construction increase steadily over the last year. Not to the point of concern for oversupply, but certainly to the point where buyer urgency is not as great.”
Tell that to the people like Hynes who are watching their condo values drop in price since 2008 instead of going up.
Because buyers know there is another building coming up, they aren’t pressured to buy, adds Urban Analytics’ analyst Jon Bennest.

“In some markets where there’s a lot of supply and not as much demand, it’s hard to say that we’ll see a price increase. In others where there is less supply and consistent demand, we do see those areas increasing. So it’s very specific to the submarket,” says Mr. Bennest.
Enter Bob Rennie and his "Transportation, transportation, transportation" mantra.

The bulls will claim that with the city population steadily growing by about 37,000 people a year, the condo will remain the only affordable housing option for a lot of people. And the people with real equity – foreign investors and local boomers – will continue to look to them for investment.

But how long will we continue to cling to the dream that wealthy foreigners will support and maintain our over inflated market?

For property owners like Hynes, who are already in a loss position,  they are now like the stock buyer who refuses to cut their losses.
Hynes says he’ll hang onto his condo long enough to see that happen.

“I’m in a situation where I cannot afford to sell it, so I’m going to be renting it out, probably next month.
(Hynes now has a family and says he will rent out his condo and use the money to rent another place, in an area with better value.)
“For me, it feels as if I am moving backward in life, but I have no choice, because I need to move on because I have a family now. I am going to move out and go rent a basement suite in Coquitlam.

“I know a lot of people can’t afford their mortgages because there are tons of cheap basement suites in Coquitlam.”
Exactly.

You can't help but survey the scene and think of the Financial Times' conclusion of the debt situation in China we talked about in our last post: "Plenty of tinder, lots of fuel, all it needs is a spark"

And when that spark comes you know things will ignite rather quickly.


==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Saturday, September 7, 2013

China's Debt Addiction: "Plenty of tinder, lots of fuel, all it needs is a spark" - Financial Times


Many believe that when China's bubble bursts, Vancouver's housing bubble will well and truly implode. 

Until five years ago, China’s economy relied remarkably little on debt. But China lost its debt inhibition in late 2008 when the global financial crisis erupted. With growth slowing sharply and 20 million people losing their jobs overnight, the government unleashed a giant stimulus that was powered almost entirely by bank loans. The debt genie was out of the bottle – and it has been extremely difficult since then for China to stuff it back in. 

In this video from the Financial Times, Simon Rabinovitch reports from Guiyang.

(hat tip 'Best Place on Meth')

==================
Photobucket
Email: village_whisperer@live.ca Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Friday, September 6, 2013

"Money for nothing - Inside the Federal Reserve" Canadian Premier @ Vancouver International Film Festival Sept. 29, Oct. 5, & Oct. 8


Those who have followed this blog know the emphasis we have placed on understanding monetary policy as an important component in knowing our housing bubble.

And an important component of understanding monetary policy is understanding the US Federal Reserve.

On November 15 the movie, "Money for Nothing: Inside the Federal Reserve" had its world premiere at the International Documentary Film Festival in Amsterdam.

Money for Nothing is narrated by Liev Schreiber. It is an independent, nonpartisan, feature-length documentary film.

The cast includes prominent Fed watcher James Grant of Grant's Interest Rate Observer. Also appearing in the film are former Fed Chairman Paul Volcker; investor Jeremy Grantham; former Vice Chairman of the Fed Alan Blinder; Peter Fisher, former Under Secretary of the Treasury for Domestic Finance; Philadelphia Fed President Charles Plosser; Richmond Fed President Jeffrey Lacker; Vice Chair of the Fed Board of Governors Janet Yellen; and many more.

Money For Nothing covers 100 years of Fed history and, in many cases, is quite critical of Fed policies. The film asks the question: Can the Fed learn from its past?

The movie pays homage to Volcker and lays out thoughtful and respectful criticism of former Chairmen Arthur Burns and Alan Greenspan and current Chairman Ben Bernanke, among others.

The movie's director, Jim Bruce, says the goal of the film is to create informed debate that exposes the impact of Fed policy on the U.S. economy and on society (from the Greenspan Put to the Bernanke Put). The film questions the rationale behind today's Fed actions and calls for better policies in the future.

Starting with the Panic of 1907 and ending with the risks on the horizon of today's quantitative-easing quagmire, Money for Nothing dramatically and entertainingly reveals the Fed's ongoing reluctance to shed old ideas. The movie is filled with wonderful narrative and fascinating images that capture the world of finance throughout the Twentieth Century.

On September 29th, October 5th and October 8th, the film will be making it's Canadian Premier with three showings at the Vancouver International Film Festival. Click on the highlighted link over the dates to go to the VIFF website for film details and ticket buying info.

For info on showings in other cities see http://www.moneyfornothingthemovie.org

It should be very interesting.

If you can't view it, the link to the video above is: http://vimeo.com/50095912.

You can also see it on Youtube at: http://youtu.be/cMxGvdgzfHw.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Thursday, September 5, 2013

Vancouver Real Estate agent dismisses August numbers as "meaningless information"


As realtor Larry Yatkowsky tells us, the press release from the Greater Vancouver Real Estate Board is all warm and fuzzy because of the August real estate numbers.
According to the Board, “August activity in the Greater Vancouver housing market finished well above last year’s pace and slightly below the 10-year average for the month.” To this is added that residential property sales in Greater Vancouver increased 52% compared to the same month in 2012. The not so fuzzy stuff is that August sales declined 14.7% from the month before and less fuzzy is that the market is still 4.6% below the 10 year average.
So the bottom line is that the market is still well below average.  So real estate isn't exactly churning along at the gang buster hype the news would have you believe.  It's just not incredibly dismal as what we've witnessed over the preceding 8 months.

Interesting.

That's a message that John Grasty, a real estate agent from Port Moody, would like to make clear to you.

Grasty is a real estate agent who bills himself as a 'homeowner advocate'. And he is front and centre in a 24hours newspaper article that proclaims 'Real estate numbers can deceive.

Now we all know the real estate industry are masters of the type of number crunching that would make even theoretical physicists blush, but its rare that we hear dissenting commentary from members within the industry.  And Grasty wants you to temper your reaction to the industry hype.

In the article, 24hours gives us the Industry spin that says real estate sales in Vancouver are reported to be on the upswing since last year but then throws cold water on that news by telling us those same numbers are being questioned by Grasty:
The B.C. Real Estate Association released figures in July showing a 32% dollar increase in home sales compared to July 2012. Analyst Brendon Ogmundson said considering how bad last year’s real estate sales were, the new numbers show a balanced market.

The association also released a report in August predicting residential sales to increase another 3.9% by the end of the year.

“The market is generally strengthening,” said Ogmundson. “When we look at year-to-year numbers are a little skewed because sales were so weak last year, but generally sales in the Vancouver region are improving and have been since about May.”
But Grasty says there isn’t much point to such analysis of the market.
“The only thing that counts is what happened most recently in sales to determine market value,” said Grasty. “If there’s a ton of product on the market, then chances are we’re in a buyers’ market.”
He said a major problem with the view of large markets is certain areas may not be reflected accurately. Just because homes in some areas are selling doesn’t mean the entire market is selling, he said.
“What’s happening when you average it all out is meaningless information,” said Grasty, adding that because some people take the predictions too seriously he has to burst their bubble when they list their home for too high a price.
What are you saying John, that the garbage we get from the real estate cartel is 'meaningless'? Can't say we disagree.

And as if to hammer that point home, the 24hours article ends with the perfect stereotypical quote from BC Real Estate analyst Brendon Ogmundson:
Ogmundson said it’s always a good time either for buyers or for sellers.
Of course it is. It's ALWAYS a good time to make a commission, right Brendon?

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.