Showing posts with label Vancouver Condo Info comments section. Show all posts

Tuesday, January 14, 2014

One blogger's take on the Vancouver Inventory numbers


An interesting post by 'Jesse' over on Vancouver Condo Info well worth sharing. For those who do not know, Jesse is the author of the Housing Analyst blog.
We concentrate on stuff like sales and listings and inventory. Here is a quick look at inventory going back to 2005, as of the end of February:

                                          1995 17377
                                          1996 17025
                                          1997 17506
                                          1998 17988
                                          1999 15663
                                          2000 14149
                                          2001 14091
                                          2002 10349
                                          2003   9692
                                          2004   7667
                                          2005 10599
                                          2006   8310
                                          2007 10414
                                          2008 11420
                                          2009 16280
                                          2010 10782
                                          2011 11925
                                          2012 14055
                                          2013 14789

The second half of the 1990s saw a steady erosion of prices and inventory was elevated for most of that time. This inventory was slowly chipped away in the early 2000s, and prices started taking off in a major way in 2002 and 2003, around when inventory looked to have bottomed. That started the last major boom from 2003 through to 2008. After the last recession inventory has been generally elevated and price rises have been more muted.

It looks like inventory at the end of February is on track to be between 13000 and 14000. This sets the “base” for inventory for most of the spring selling season and some increased competition for sellers.

Price drops (from Feb to June) in the spring in Vancouver are rare. I do not expect this year to produce price drops over that period in 2014. However given the “high” level of inventory, what looks to have been mediocre rental growth over the last year, robust completions and the purported “advance buying” due to rate rises in 2013, I do not think prices will rise significantly in the first half of 2014.

I am awaiting Vancouver population growth to mid-2013 (to be released in the next 1-2 weeks). This will provide some indication on how much Vancouver CMA has grown; growth into the region usually leads purchases by about 6-12 months as in-migrants often wait before deciding where to buy in the region after moving here.

I still think the prevailing trend for Vancouver-area property is down but I do not think it will be in a straight line. 2013 was stronger than I think will be the average over the next 5 or so years. We’ll have to see if 2014 can repeat this performance, and I would never underestimate the possibility that assets like property will be boosted by low interest rates and robust equity valuations for a few more years.
Anyone have any thoughts?

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Tuesday, January 7, 2014

Soft landing? No crash? Hmm… sounds familiar.


There's been lots of chatter in the media from numerous sources lately (including our own new Bank of Canada Governor) talking about how the Vancouver (and Canadian) real estate bubble hasn't collapsed yet and insisting the 'threat' is simply not there.

This despite the fact all the elements telling us we are in a bubble are still present.

So it's timely that gordholio over on Vancouver Condo Info has posted the following quotes from 2005 in America.  After hearing about warnings of a housing bubble for years, and seeing no collapse, the public was provided with these treatise's.
"We are really on track for a soft landing. There are no balloons popping.”
- David Lereah, National Association of Realtors, December 2005

“The retreat in housing-market activity that’s now under way amounts to a simmering-down process rather than a classic cyclical contraction that could spiral down for some time.”
- David Seiders, Chief Economist, National Association of Home Builders, Jan 2006

“The idea that we’re going to see a collapse in the housing market seems to me improbable.”
– John Snow, Treasury Secretary, 2005

“I think the bloom is off the rose, but there is no doom and gloom.”
- Alan Nevin, Chief Economist, California Building Industry Association, Dec 2005.

“There was never a “bubble”, so there is nothing to “burst”.
- Jeromith Sutton, 2006, NAR Investment Advisor
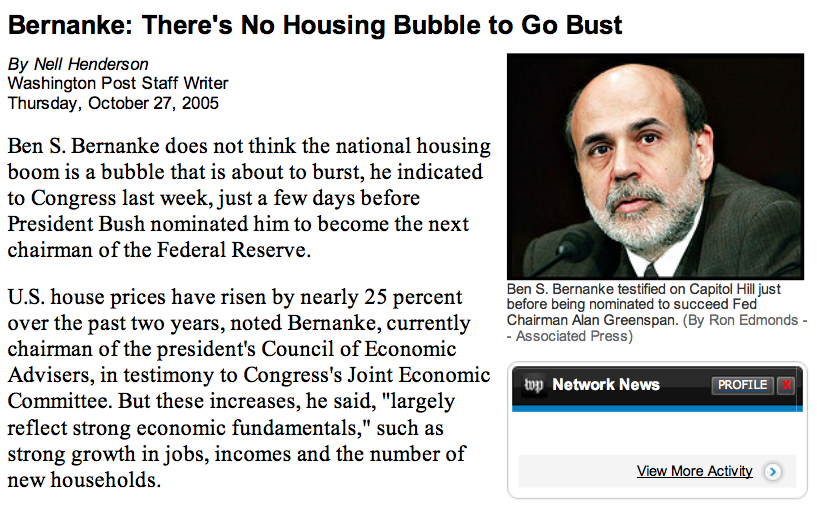
And, of course, there was America's central banker himself who in 2005 insisted there "is no housing bubble to go bust."

Sound familiar?


==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Thursday, October 10, 2013

Vancouver's foreclosure rate running at 6 per day in October 2013


As mentioned in the last post, Ham Solo has been posting daily foreclosure data on cases filed in BC over on the blog Vancouver Condo Info.

As of October 10th, there have been 48 foreclosures in the City of Vancouver.

That's a rate of 6 per business day at a time when record setting cheap interest rates are supposed to help people pay off their debts.

It speaks volumes.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Wednesday, October 9, 2013

Pre-sales closing crunch in Toronto? And... Vancouver foreclosures running at 6-7 per working day.


Debt is endemic. They use lines of credit to make mortgage payments. They routinely increase the size of their home loans to renovate. Four in ten people now say they have trouble paying their monthly bills. And yet 70% own a house. Prices have been bloated by cheap money, not greater income.
That's a quote from one of Garth Turner's posts (May 16th, 2013)

Mortgage brokers, realtors and developers have seen a surge the last few months in people who bought pre-construction condos two to three years ago “scrambling” to get financing to close deals. 
Some have had to walk away from deposits worth tens of thousands of dollars. Others have been forced to borrow from family — or against their principal residence — to come up with final payments on condos that lenders are no longer keen to finance, according to interviews with a number of players in Toronto’s condo industry. 
Hardest hit have been the self-employed who had pre-approvals from lenders when they bought their pre-construction units. But now, with the unit almost complete and final payments due, they are being told they need 35 to 50 per cent down, instead of just 20 per cent of the purchase price, unless they want to rely on secondary lenders offering rates that can hit double digits. 
Many investors who bought units intending to flip them on completion, or rent them out for a few years, have also been shocked to find they thought they had pre-approvals, but they are no longer being honoured in the wake of tighter lending rules imposed by Ottawa.
Can you imagine what things will be like if the Federal Government responds to the idea that mortgage debt is a threat to the economy?

Or if interest rates really do start to rise?

On another note, an interesting post over on Vancouver Condo Info from Ham Solo


From the start of the last paragraph: "Looking at a couple of weeks of data, adjusting for double-counting, we are seeing Vancouver foreclosures totalling about 6-7 per working day."

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Saturday, November 3, 2012

A New Boom? Or an appeal to greed from an angry shyster?


Interesting tidbit in the Wall Street Journal the other day.

The WSJ was chronicling the plunge in Vancouver home sales. At the end of the article Flaherty is quoted commenting on the impact on house sale.

As the Journal analyzed the Vancouver situation, they observed:
There are several factors slowing the market. The Canadian economy has slowed along with the rest of the developed world. But a series of recent policy changes enacted by the federal government in Ottawa have had the most impact, according to Realtors, marketers, lawyers and bankers. 
This summer, Canada's immigration minister temporarily froze two programs for immigrants: the Federal Skilled Worker Program and the Immigrant Investor Program. The latter program grants citizenship in five years to qualified immigrants who agree to invest at least C$800,000 in Canada. Real-estate agents said the freeze, which ends in January, has slowed buying from Chinese.
 Will the end of this freeze lead to another resurgent boom in Vancouver Real Estate?

Over on the VCI blog there have been a string of angry comments from the contributor IamTheChipman.

In one Chipman says:
You Shitbirds will be disappointed yet again. 
The WSJ article highlights how the Canadian immigration rules will change again in January. Watch houses in Richmond and the Westside EXPLODE higher. 
Can’t you read the tea leaves when it’s that EASY! 
I’d be buying now and flipping in a handful of months, if you did this with a few properties you could easily score a million or more in 5-7 months with perhaps 10-15 hours of total effort. 
Yes, I know for the average goofball on this blog that’s chump change, but for the rest of us mere millionaires it’s a decent return on our capital. Your invited to the party, all you have to do is say yes.
One thing that has always perplexed me is why contributors like him bother with the effort.

I mean let's face it.  When someone has opportunities to flip for sure fire gains, they are out making the purchases. Then they sell, realize the profit and look for another opportunity.

One thing they don't do it is waste time posting to a blog that is primarily focused on the complete opposite of what they are advocating in the hopes they will convince someone to go against the grain and buy.

So why make the post?

I think the likes of IamTheChipman are worked up because so many people are now reading blogs like VCI, and are finding strength in the message being conveyed.

They post as a way to vent their anger at that message.

I have a feeling the market's changing dynamics have a lot of people on edge,

We can read the tea leaves and - yes Mr. Chipman - it is that easy. I think we will say, "no thanks."

The real question is, why does it bother you so?

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Friday, October 26, 2012

It's not just the million dollar homes falling below assessed value

L


Reading this blog you know we are watching the comments of the likes of BCREA chief economist Cameron Muir and UBC Sauder Associate Professor Tsur Somerville with keen interest.

Last month we have Somerville saying:
“Most people don’t have to sell their house,” he said. “You bought it for $200,000. The price is now $150,000. Unless you have to, why would you sell it?” 
For prices to go down ­significantly, contended Somerville, “You need people who have to sell, either because the economy has collapsed and they don’t have any income or developers have built a whole bunch of units that are unsold and the bank is screaming at them or foreclosing or something like that.”
None of those conditions appears imminent. 
This week he changed his tune and said Vancouver home prices could drop by 10% next year.

Meanwhile Cameron Muir insists:
"we don’t see a recession on the horizon, and we don’t see interest rates going up any time soon, so what kind of financial calamity is going to happen in Vancouver to get people to sell for 75 cents on the dollar?
We've shown you examples of Vancouver detached houses that currently have asking prices 23% below assessed value and Richmond detached houses 25% below assessed value.

Some have suggested that these are these extreme examples and that no such worry exists on the lower end of the spectrum where the average Vancouver income earner resides.

Without getting into the debate about whether the 'average Vancouver income earner' is into million dollar properties or not, a quick check of the comment section on the excellent blog Vancouver Condo Info turns up an immediate example to reference (hat tip Teddybear).

Here is an example of a Vancouver condo from a lower price range.

This is #2905-438 Seymour Street in the downtown core of Vancouver (click images to enlarge): 


It's a 1 bedroom, 1 bathroom condo which is currently listed at $319,000.

The $319,000 asking price, btw, is a big reduction.  It was originally listed for $389,000 on August 20th, 2012.

Now for those that discount that a $70,000 asking price cut (detractors will tell you idiots can always ask wild prices, doesn't mean squat in the big picture), the real test comes when we look at the assessed value:


As you can see... this property is assessed at $376,000.

So in a so-called 'flat' period (according to Somerville), the owners of this property have cut their asking price to more than 15% below assessed value.

Toss in another 10% drop in value next year (again... according to Somerville) and you have a property that would come in at 25% below assessed value.

Muir wants to know what is going to happen in Vancouver to get people to sell for 75 cents on the dollar?

Perhaps he should give the folks at 498 Seymour Street a call and ask them?

I suspect it has something to do with the fact that the listing indicates that this is the first time this unit has been on the market since the original sale. 

The building was built in 1996. Since then we have seen a huge loosening of credit (which triggered our massive housing boom -see our post here).  As a result it's not hard to surmise we have a situation very similar to the Boomer Trigger - i.e. people can move on price, so they will - and in doing so they still get out with a healthy capital gain.

This is an element that both Muir and Somerville appear to completely ignore. Many of these people selling for below assessed value aren't taking 75 cents on the dollar for their original 'investment'. 

It's a factor could wind up having a profound effect in the coming year.

If anyone knows the original purchase price of this unit, it would be nice to compare that to the current asking price/current assessed value  - let us know.

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Thursday, June 28, 2012

Seller's Unite!


On Tuesday we were telling you just how bad it is for real estate sales in Richmond right now.

Realtor James Wong's monthly R/E report, released June 16th but covering the May 2012 sales data, advised that total listings have hit all time highs, daily price reductions are common, and detached home listings in the million dollar plus category are dying on the vine.

Of the 556 homes on the market with an asking price north of $1,200,000, sales have been so bad that there were 17.7 months of inventory on the market by the end of last month.

Wong's advice to sellers was blunt: If you have to sell, much deeper price cuts are needed.

And if the data from the month of May was bad, June's results are abysmal.

Using sales reported between May 27, 2012 and June 26, 2012, and actives as of today... there is now 23 months of inventory on the Richmond Real Estate market.

Word has it that for the majority of those rare sales that are occurring, most are closing below assessed value of the property as some sellers are obviously taking Mr. Wong up on his sage advice.

But as you can imagine, this is causing a great deal of consternation for other Richmond sellers.

One Chinese real estate forum is calling on 'sellers to unite' to prevent further price drops. (hat tip to VMD on Vancouver Condo Info).
“A brand new house in good area of West Richmond, 8111 Dalemore Rd, was just sold for $1.58M, $170k lower than assessed price of $1.75M. It’s a shame that the (owner) went through so much to purchase this property and build a new house, hoping to earn some money while doing a service to the community, only to (then) recklessly slash (the) price. I call on the sellers to withhold giving in to under-asking offers. We should all pull our listings and wait until a better market to sell in a bidding war situation”
Of course, as VMD notes, do not lament too long for the hardships endured by the seller at 8111 Dalemore Road.


The 5 bedroom, 5 bath mansion was built in 2010 to replace an old-timer teardown which last changed hands for $533,000.

And while the property did recently sell for $170,000 below the 'current' assessed market value of $1,750,000, a final sale price of $1,580,000 hardly qualifies as hardship for this seller - right?

Or does it?

Maybe it really is "a shame that the buyer went through so much to purchase the property and build a new house" and not have it sell in the type of bidding war that one year ago would have realized offers of $300,000 - $400,000 over asking.

Perhaps I am being callous to the needs, hopes and dreams of the Richmond speculator?

Proletariat Unite! Protect the Richmond real estate flipper now!

==================

Now on Twitter @village_whisper

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Tuesday, June 5, 2012

Random thoughts


A few random items for you this morning.

(1) On the topic of HAM

The topic of Hot Asian Money (HAM) in Vancouver is a strong one. There have been lots of stories about how west side houses have been snapped up by HAM and sit vacant (the Courier newspaper did an article about this, but I don't have the link at the moment).

In a report released by the Bejing News, google translated here, Bejing alone has 3.8 million vacant houses, presumably bought by speculators in the real estate frenzy there and those homes are being held for the right time to 'flip'.

3.8 million?  Even in the United States, five years into a bursting housing bubble, it is estimated only 2.54 million homes are available for SALE!

Imagine the panic to dump if the China/world economy turns significantly downward?

(2) On the topic of Vancouver Speculators

Speaking of not ending well, a discussion went on the other day over in the comments section of the blog Vancouver Condo Info. Contributor 'Patsan' noticed that one person (Gary) was advertising 3 homes for rent on the west side of Vancouver and the tone of the craigslist ad seemed 'desperate'.

I noted that if the phone number listed was 'googled', there were a whole host of properties available for rent from this 'Gary' person. One diligent reader of the site did some research and noted:
"This Gary guy has at least 12 West Side and Richmond properties advertised for rent. They are all vacant and available now and if you goggle the address all were recently purchased. Most of the properties on the West Side sold for close to 3 million and the Richmond ones are in the 1.5 million range. The guy must be a rental agent or ring leader behind investors who have recently dropped at least 20 to 30 million on houses to rent. The ads all state minimum 1 year lease so they are not looking for quick flips. None of the ads have photos or much details. The guy doesn’t have any houses advertised that appear to have been previously rented so he must be a newby to the game."
And this is just ONE group of speculators in Vancouver.

Now multiply Gary's group by a couple of hundred and imagine the speculative panic here if the housing market in Vancouver turns downward.

(3) Comparing Statistics

Speaking of the euphoria that buyers were in a year ago, contributor VMD over on Vancouver Condo Info posted some comparisons of single family home sales from last May 2011 to this May 2012 to show just how bad sales are this year compared to last year.

1. Van West
Sales YoY -47%
Lists YoY +36%

2.West Van
Sales YoY -59%
Lists YoY +23%

3. Burnaby
Sales YoY -38%
Lists YoY +23%

4. Van East
Sales YoY -28%
Lists YoY +26%

5.Coquitlam
Sales YoY -21%
Lists YoY +21%

6. Richmond
Sales YoY -20%
Lists YoY +11%

VMD notes Richmond was the first to slow down last spring, so its numbers were pretty bad last May. This May is even worse.

Will Boomers pull the trigger in greater numbers as the market worsens and slash the price point they will accept even more? Thus pushing the drop from 12% to 20%?

Could the drop accelerate even greater than that?

(4) If we slide downward, how far could we go?

If you follow this blog, you already know my thoughts.

Consider this musing from Vancouver realtor Larry Yatkowsky who broaches the concept of a 32% drop in prices:
Let’s start at the highest average price ever reached in Vancouver for a detached home – a mere $1,235,244. Now let’s also assume this market is on the skids sliding down the drain faster than we think to bottom out at something most of us would not imagine – a market that drops so much it hits May 2009′s Average Price of $831,171.

With a price drop of $404,073... that's a 32% drop from the all time high.
Consider that a 32% drop in prices only takes us back to 2009.

Larry argues buyers will rush in at this point (and I agree), but rather than establish a bottom for the 'correction' - I can't help but recall the 'phases of a bubble' chart:


A rush of buyers into the market at this point would just about reflect these phases perfectly, wouldn't it?

Can you see all the pieces falling into place for a significant drop?

Is a 70-85% collapse in prices still all that hard to fathom if these elements come to pass: The China Trigger + The Speculator Trigger + The Boomer Trigger?

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Sunday, July 31, 2011

Some Sunday musings


A few random thoughts first thing this Sunday morning.

Yesterday we noted how the chief economist for RBC Global Asset Management, Eric Lascelles, argued that by the time many current mortgage holders renew their mortgage that the impact of higher interest rates will be mitigated by three years of rising household incomes.

It is fitting that on the day his comments were covered that shocking GDP figures were released showing that Canada's gross domestic product unexpectedly fell by 0.3 percent in May and that the U.S. economy grew at a meager 1.3 percent in the second quarter.

More importantly growth for the first quarter was revised sharply lower.

And just as data from the first quarter in the US was 'revised' lower, analysts are already looking at the second quarter data and figure that it's not accurate either and will be downgraded as well.
  • "Just as Q1 2008 was eventually shown as the start of the great recession so will Q2 2011 in subsequent revisions."
So much for three years of rising household incomes.

Speaking of conditions stagnating, former Chinese central bank adviser Yu Yongding repeated his call for China to reduce its Treasury holdings as the American debate about the debt limit drags on. Speaking to reporters at a briefing in Mumbai on Friday Yu said:
  • “U.S. bonds are not safe, but people think they are safe. That is a mirage.”
In March, Yu said that China, the biggest foreign holder of Treasuries with $1.16 trillion of the securities, should halt purchases because of the risk of an eventual default. In June, he predicted that credit agencies would limit the severity of any downgrade of the U.S. rating to avoid investor panic.

As China, Russia, Japan et al slow their purchases of US Treasuries, the US Federal Reserve will have no choice but to launch some form of QE3 to monetize the US debt. Increasingly the US economy (and by extension: Canada's economy) look to be entering the same decade plus malaise that Japan is dealing with.

There was an excellent analogy offered in the comments section over at Vancouver Condo Info yesterday about the actions our governement took during the first phase of the financial crisis (2008-2011):
  • "The low emergency rates were supposed to be used as a spare tire, while the regular tire was to get fixed. But they couldn’t afford the repair, and could not buy a new tire as the credit card was maxed, so they ran the spare tire so long the tread is worn and can’t get any traction."
The economy has stalled and conditions are not improving. As the real estate market turns, the impact on Lower Mainland homeowners with high mortgages is going to be severe.

Our friends over on VREAA documented a poignant comment yesterday which represents the situation shared by many who have bought in the last five years in the Lower Mainland.  Calling into the Bill Good radio show, a caller said:
  • “I work long hours to be able to pay for a house. I drive long distances to get to and from work. I barely do anything in my expensive house other than sleep and go back to work each day. And on top of that [speaking about the upcoming additional gas tax] every time I turn around I’m being taxed for something else.”
Bill Good replied that he thought the caller was "speaking for thousands of people right now.”

Indeed he is.

==================
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.


