Showing posts with label BCREA calm fears of crash. Show all posts

Thursday, January 31, 2013

Thur Post #1: CTV BC: Experts predict BC's real estate bubble will remain intact (played to the tune of 'when you wish upon a star')


Oh Tamara... really?

Is this the price we pay so that you can hang out regularly in Aquilini's box at Canuck games?

CTV BC came out with the above shill piece for the real estate industry's on-going campaign to tell you the real estate bubble won't burst - so you best buy now.

Sigh.

And the reason?

Supposedly, according to one real estate agent, there's "optimism in the air.  People are feeling happy, phones are ringing, it feels like we're back into selling real estate."

So it that what were hanging our hat on right now?  Attempts to manipulate buyer confidence?

Then we are fed the BS line that "new numbers are out today from the BC Real Estate association that back this up... signalling better times ahead"

Oh?  And what numbers are those?

Well BCREA pumper in chief, Cameron Muir, tells us that "the fundamentals in the market suggest that home sales should be stronger, higher than the levels were currently seeing."

Based on this wishful thinking we are shown this highly manipulative graph which - as the narrator tells you - is that "based on this, homes sales SHOULD be higher this year and next":

Really? Cameron claims his fundamentals say sales SHOULD be higher so we therefore forecast a 5.6% increase in sales this year and a 6.1% increase in 2014?

Then comes the gushing excitement that based on the fantasyland belief that sales "should be higher", then this means this "forecast uptick in sales is great for developers"  

Completing this daisy chain of fabricated logic is the Omni developer who says "we're seeing some real positive movement that buyers are coming off the fence."

Huh? OMG!

So... it's all about wishful thinking, now? That's what is going to make it all happen? And this passes as NEWS???

Incredibly that seems to be the level of desperation we're at.  Play the media with nothing more than BS to create the ideal that the market has no place to go but up in the hopes of creating some kind of buying frenzy.  Then you hype the 'fantasy frenzy' to manufacture the belief that a real estate uptick is underway and about to crest in the Spring air.

As always - you best buy now or be priced out forever.

Riiight. I truly believe we hit a new level in pathetic with this one.

==================
Photobucket

Email: village_whisperer@live.ca  Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Thursday, January 3, 2013

The correction going on in Vancouver is a "fairly sizable one" - RBC


Meet Paul Ferley, Assistant Chief Economist at RBC Capital Markets.

Ferley captures out attention for some comments he made on the Business News Network earlier today.

BNN was running a story on December's real estate numbers which showed Vancouver home sales plummeting again.  BNN started of talking with Cameron Muir, the Chief Economist from the B.C Real Estate Association.

Muir comes on the program carrying the "there is no bubble" standard that he and Tsur Somerville have been pounding for the last little while.

He insists that, after surviving the Great Financial Collapse of 2008, if the Vancouver Real Estate market hasn't collapsed yet then it won't.

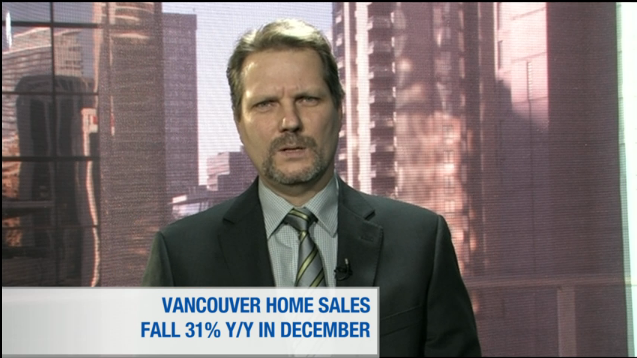
As if to point out the absurdity of his comments, while Muir was insisting the Vancouver market has been 'flat' since 2008/2009, BNN flashed across the screen the fact that Vancouver home sales were down 31% year over year in December.


BNN notes how jarring the statistics for sales declines are. Does this not concern Muir?

As always our buddy Cameron dismisses the poor sales, insisting all signs are for positive growth. Muir jumps on the fact that November and December saw sharp pull backs in the number of listings on the market - conveniently ignoring that this happens every year in November and December.

But as we showed yesterday, the number of active listings on the market right now is far higher than in previous years.

BNN contrasts this with comments from Paul Ferley, assistant chief economist at RBC Capital Markets.  Ferley says the bank's research on housing affordability in Vancouver showes that prices in the city had become frothy.
"Certainly the Vancouver numbers have been suggesting stresses in that market with affordability deteriorating and at some point a correction was likely going to have to play out. It was a market looking like it was poised for a correction."
Ferley adds that while prices have yet to fall as dramatically as sales, the city could be headed for "double digit" declines in home prices.
“You're seeing a correction in Vancouver – a fairly sizable one."
The focus on the Spring Market ramps higher with each passing day and the stage is set with Muir and Somerville firmly staking their reputations on a crash not happening.


(hat tip VREAA for Van. Sun image)

==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Thursday, December 20, 2012

"The price increases of the last decade are long gone."


You've got to wonder just how significant the shifting mindset amongst the public is regarding real estate when even Global TV is now openly saying the following:
"... there hasn't been a crash, thankfully, but Ottawa and the Bank of Canada are desperate to raise interest rates once the economy improves. Economists are expecting the rates to start inching upwards by late 2014 - meaning the price increases of the last decade are long gone."
Kinda kills the whole campaign to get people to buy the current dip, doesn't it?

Of course the same talking heads who want you to buy the current dip also want to insist there is no dip - prices are just flat and will remain flat (real estate never goes down, don't you know?).

Meanwhile Cameron Muir wants you to know that:
Last year’s figures must be taken “with a grain of salt,” Muir said because the prices were inflated by a large number of luxury homes for sale in West Vancouver, Richmond and Vancouver’s West End.
Really?

In all the breathless monthly reports we saw last year from the BCREA, does anyone recall being told to take those figures with "a grain of salt?"

Muir also wants you to know that:
"The federal government’s decision to reduce the maximum amortization period for a government-insured mortgage to 25 years from 30 years also affected home sales.

That could add up to $160 on the monthly payment of a $350,000 house.

That no doubt has squeezed some potential buyers out of the market."
So buyers are extending themselves so thin that an extra $160 a month collapsed the real estate market?

If so, imagine what a few interest rate points might do?

(hat tip to LM and GreenhornRET)

On another note, isn't the world supposed to end tomorrow?


==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.

Saturday, October 27, 2012

Media notes R/E groups attempting to "calm fears of a local housing crash"


On Thursday we told you how the media was filled with economists and 'experts' who were now predicting that prices will, in fact drop, but will do so by a moderate level that does not resemble the U.S. crash.

The purpose of all these ascertains? Preventing panic. A fact the Vancouver Sun noted yesterday:
Greater Vancouver will see home sales tumble by one-fifth this year, but the market should rebound in 2013, the B.C. Real Estate Association says in its new forecast as the group moves to calm fears of a local housing crash.
It is exactly those types of fears which are encouraging sellers to accept 75 cents on the dollar for properties (examples of which we have profiled over the past couple of weeks).

Of course the sellers aren't actually taking only 75 cents/dollar on their real estate.  Most bought before the big blow-up of the bubble during the 00's and they are still enjoying a large capital gain.  They just see the writing on the wall and are cashing out while there are still profits to be realized.

And those signs are everywhere.

Vancouver movers are reporting stiff declines in business due to the falling real estate market and the slowdown is effecting a broad segment of society:
Tradesmen, Builders and Craftsmen, worry about the later half of 2012 and the speculation around the slow down of the Vancouver Real Estate Market... Competitively priced houses are now sitting on the market for an average of 5 to 7 months. 
Scott Moe of RE/MAX says: "All across the board people are saying how slow it is out there. I have 24 listings right now and only had 4 showings on the weekend!" The slow down of BC's real estate industry extends well beyond just builders and realtors. Many local businesses are affected by slow real estate sales.
Which is why early signs of panic are now starting to pop up.

And there signs of more problems ahead.

Concerns are spreading through the Chinese media with headlines that: “All Canadian banks will introduce new mortgage rules by November 1st, 2012”What will those new rules entail?
All-Canadian banks and financial institutions will start on the 1st of next month to take up increased tightening housing mortgage measures. There will be new rules for those without sufficient proof of income documents.  This will include the self-employed who will only be able to obtain no more than 65% of the mortgage property value in their loans. Prior to the implementation of the new requirements, some banks allowed self-employed people up to 75-80% of property values in a mortgage. 
Mortgage experts believe that the new measures will have the greatest impact on new immigrants.
As one contributor on VCI noted (hat tip VMD), the OSFI will require lenders to limit maximum LTV ratios of “nonconforming residential mortgages” (eg. Self-employed without adequate income verification) to 65%, meaning the borrowers will need to put 35% up as a down payment.

New immigrants will be impacted due to inadequate income documentation, which looks at average income of the last 2 years. - (Previously new immigrants were required to put down 30% DP) - 

HELOC LTV limitations will be implemented by Nov 1st as well.

In other words, the saviour of wealthy Asians buying our overvalued property at prices high above what local incomes can support is about to take another big hit.

Combine that with tightening regulations on what entry level buyers can now overspend on greasing the property ladder at the entry levels and you have a recipe for even steeper declines.

Perhaps that's why a Winnipeg real estate agent is now running this ad (hat tip Makaya):


 ==================

Photobucket
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.

Please read disclaimer at bottom of blog.