Saturday, June 23, 2012

CMT's 20 Observations on the New Mortgage Rules


Canadian Mortgage Trends came out with an interesting post today titled 20 Observations on the New Mortgage Rules
It's reposted here for your convenience...
====================

Three months ago, Finance Minister Jim Flaherty told banks totighten lending on their own. Now he’s doing it for them.
The Department of Finance (DoF), in concert with OSFI, released a buffet of mortgage rules Thursday. By our count, there are eight salient changes that, when combined, will have a measurable impact on housing.
See: New Mortgage Rules and OSFI Guidelines [B-20] for rule summaries.
The motivation for these moves is captured in Flaherty'spress briefing comment: "I have been listening to the market, and quite frankly I don't like what I hear.” Loose translation: The debt and housing train is in danger of running off the rails.
The DoF's solutions to this problem will influence our market for years to come. Below are 20 musings on the new mortgage rules, sprinkled with a few tips and predictions:
1. Hurried Implementation:
mortgage-rule-implementationThe government knew full well that borrowers would try to front-run these restrictions. So it provided only 18 days lead time until the changes take effect. Most lending execs had no idea that new mortgage insurance rules were imminent. As a result, lenders were not fully prepared.
Because of this, and because banks like to appear prudent to regulators, there's a chance some lenders may implement rules (like the 25-year amortization restriction) before the July 9, 2012 deadline.
2. The Stampede:
Mortgage-rule-rushSeemingly every mortgage adviser in the country is blasting out emails advising clients about these changes. The sense of urgency will spike mortgage volumes near-term. But high-ratio borrowers who rush to get a 30-year amortizationor 85% loan-to-value (LTV) refi should be warned:
  • Underwriting during the interim period (June 21-July 8) may be especially vigilant, in an effort to weed out the marginal borrowers who spring from the woodwork
  • For the next three weeks, the lenders with the best rates, or those that are less efficient or less staffed, could have abnormal underwriting delays (keep that in mind if you have financing condition deadlines)
  • In most cases, mortgage rule changes are not a reason to rush a home purchase.
3. Rate Warfare:
Battle tank cutoutIf you’re a well-qualified borrower, you’ll be happy to know that you just became more appealing to lenders. These rules will shrink the pool of prime borrowers. As a result, we’ll see bankers and brokers battle harder for your business. That means the rate wars that Flaherty “discourages” will intensify, whether banks publicize it or not.
4. Side-Effects:
affordabilityShorter amortizations, higher qualification rates and lower debt ratio limits will restrict buying power. To that, Flahertysays: “Good. I consider that desirable.”
Canada's 9.6 million existing homeowners, however, may not deem it so desirable—not if these actions trigger a bigger or longer-than-normal selloff that jeopardizes their home equity.
Equity is the biggest source of retirement savings for millions of Canadians. For this reason, even Flaherty would admit that these proposals are essentially a calculated gamble.
On the other hand, waiting for the market self-correct has its own risks, namely a much longer economic recovery if the speculative balloon is punctured.
Either way, the market is propelled by payment affordability. Reducing buying power will weigh on prices. Whether other supply/demand factors offset this pressure is unknowable.
The DoF wants Canadians to believe the side-effects won’t be extreme. And, if market reaction is anything like the 2008, 2010, and 2011 mortgage changes, it won't be.
Flaherty states that "less than five per cent of new home purchasers" will be affected by these changes. If he simply means buyers of brand new homes, five per cent equals ~9,600 people a year (based on CAAMP's 2012 housing starts estimates).
If Vegas made an over/under line on that 5% figure, we’d bet the “over.”
In the new-build market, there are 95,000 first-time buyers each year alone. If you include new and resale purchases, there are roughly 261,000 newbie buyers annually. These are people who are disproportionately affected by these changes, albeit a minority of them.
On top of this you have a minimum of five per cent of repeat buyers (20,000+ a year) that will likely be curtailed by the rule changes to amortizations, qualifications rates, stated income, and debt ratios.
5. The Amortization Effect:
Reducing amortizations to 25 years from 30 chops the maximum theoretical mortgage by roughly 9% (versus ~7% when amortizations dropped from 35 to 30 years). That’s equivalent to paying almost 1% more on your mortgage rate.
Put another way, a qualified family earning $75,000, with no debt, will qualify for $49,000 less mortgage by being forced to take a 25-year amortization.
amortization-comparisonAccording to CAAMP, 40% of new mortgages last year had amortizations over 25 years. Of all the new rules, this will have “the most direct impact on the Canadian housing market,” states RBC. It “will raise the barrier to entry into Canada’s housing market.” (That is Flaherty's point, of course.)
TD thinks it could take up to a year for changes like this to negatively impact prices. But some expect a more imminent result.
Robert Kavcic of BMO Nesbitt Burns notes: “After the 35-year amortization was eliminated last March…existing home sales fell by more than 3 per cent over the subsequent two months.”
6. Market Stability:
Most industry observers, ourselves included, believe in the merits of shifting some housing risk to the private sector and building savings rates. "Our economy cannot . . . depend indefinitely on debt-fuelled household expenditures, particularly in an environment of modest income growth,” explains BoC chief Mark Carney.
The government adds that these new rules will bring “long-term stability” to Canada’s real estate market. Note: They say “long term” because they know the effects could be adverse in the short term. The DoFcalls that risk “manageable,” however.
Home prices, which are already self-correcting in various regions, will see additional pressure as payment affordability drops. (Ironically, a correction in prices would then, in theory, improve affordability.)
Flaherty has “tapped the brakes at precisely the right time,” says BMO CEO Frank Techar. From our viewpoint it's more like stopping short than a little tap.
All one can hope for is that the brakes don’t lock up, with mortgage affordability being so intimately related to home prices.
That’s partly why the Canadian Association of Accredited Mortgage Professionals (CAAMP) feels the government has “overreached” with this latest round of changes. In a statement Thursday it said:
“CAAMP believes that Canadians understand the importance of paying down their mortgages. These changes, together with new OSFI underwriting guidelines…may precipitate the housing market downturn the government so desperately wants to avoid.”
But heck. With housing-related activity comprising 1/5 of GDP and resale housing adding ~$20 billion in spending and 165,000+ jobs this year, what’s the worst that could happen?
7. So Much for High-Ratio Refis:
Refinance-MortgageRefinances above 80% LTV will soon be a memory at primelenders. Refinance volumes will then fall off a small cliff. The last time the Ottawa lowered LTVs on refis, insuredrefinances tumbled 22% (source: CMHC).
The result will be more people being saddled with high interest debt that they can’t refinance. (Insert your favourite home-ATM analogy here.)
We’ll also see home improvement spending slow. The renovation business is a $66 billion industry and $17+ billion a year is financed with mortgages and HELOCs. (Reining in overleveraged and chronic home renovators is healthy. They are a small wedge of the refi pie, however.)
If you own an average priced home, you’ll be able to refinance $18,780 less debt to your mortgage. If your rate on that debt is 19.99%, for example, the 80% LTV refi restriction could cost you an extra $9,000+ in interest (or more if it takes greater than five years to pay off that rolled-in debt).
On the upside, a loan-to-value ≤ 80% would save you $5,587 in default insurance premiums.
Now more than ever, it will pay to have a competant mortgage adviser run the math and compare all your refi options.
8. Non-Prime is Where It’s at:
ProfitAlternative lenders like Equitable Trust and Home Trust are lovin’ life. Their target market has just expanded as regulators force banks to turn away more near-prime borrowers.
If alternative lenders can manage defaults through the eventual housing downturn, they’ll profit handsomely from this volume boost. We're talking borrowers who are less rate sensitive (because they have fewer options) and at least three times more profitable than “A” borrowers.
In addition, given greater demand for Alt-mortgages and a constant funding supply, we may see "B" lenders exert more pricing power for a period of time.
From a broker perspective, this growth in near-prime lending is the silver lining of these rule changes. Comparison shopping is important for prime mortgages but it's utterly essential when it comes to non-prime mortgages. And brokers are the only significant source for this service.
9. Exceptions:
new-BFS-mortgage-rulesIf you need a mortgage and have less than 20% equity, then as long as you apply before July 9, you will qualify under the old rules.
That’s true even if your purchase offer isn't final. “…The new parameters will not apply, even if the conditions of [a purchase] agreement have not been waived,” says the DoF.
If your application does not conform to the new insured mortgage guidelines, however, you’ll have to close byDecember 31, 2012. (See: these rule FAQs.)
Note: If your income situation, debt ratios or loan amount change, and you need to modify your mortgage after July 9, you may be bound by the new rules (even if you were already approved under the old rules).
10. Pre-approvals:
Pre-approvalIf you get pre-approved before July 9 and want to avoid the new rules, you’ll need to:
a)  Have a purchase agreement dated before July 9, and

b)  Apply for a full mortgage approval before July 9.
11. HELOC Pullback:
HELOC sales will drop once banks implement the B-20 guidelines. The reason: Fewer homeowners will meet the lower 65% loan-to-value (LTV) limit and higher qualification rates.
Fortunately, HELOCs_OSFI tells us it willnot require existing HELOC holders with LTVs over 65% to drop down to 65% LTV.
Borrowers are still able to submit HELOC applications today at 80% loan-to-value. There’s no telling for how long. As the October 31, 2012 implementation deadline approaches for the big banks, we’ll see 80% LTVs start disappearing. It could happen sooner than some expect.
In the coming days, we’ll run a piece on how HELOC LTV changes impact the Smith Manoeuvre and similar leveraged investing strategies.
12. CB D/Ps R.I.P.:
Cash-back-mortgageAccording to one high-level bank exec we spoke with, Cashback downpayment mortgages look to be dead, effective October 31, 2012 (possibly much sooner). But no lender has announced anything on this, as of yet.
Cashback refinances, however, may live—unless the DoF ends up restricting them too.
Barring that, cashback refis may get more common as time goes on.
Borrowers can use CBs to refinance to 85% LTV, via an 80% LTV mortgage plus 5% cash back. They'll have to pay a cashback interest rate (1.70%+ higher on 5-year terms), but the "free" cash effectively reduces that rate premium to about 50 basis points. CB users also avoid the insurance premiums that typically apply to 85% LTV refinances.
Just beware of the cashback clawbacks if you get one of these mortgages and discharge it before maturity.
13. Debt Ratio Double-Whammy:
debt-ratio-calculations-mortgageDebt ratios are one measure of how much mortgage you can afford. The new 39% gross debt service (GDS) limit will only impact high-ratio borrowers with a 680+ credit score. (High-ratio borrowers with scores below 680 are already capped at a 35% GDS.)
Dropping from 44% to 39% will restrict a subset of the market. Most people won’t be affected, however. The reason we say that is because the typical high-ratio buyer has a total debt service (TDS) ratio in the mid-30% range, according to analyst research we’ve seen. The latest CAAMP data on the subject estimates the TDS for all buyers combined at 32.5% (as of 2010).
That said, not everyone is immune from this GDS restriction. The new 39% cap will lower the maximum theoretical mortgage by roughly $57,000, or 12%, for a household earning $75,000. (This assumes a 3.09% 5-year fixed rate with a 25-year amortization, no debt and 5% down.)
If you combine that with the amortization reduction (from 30 to 25 years), it's quite a one-two punch—amounting to a 20% reduction in maximum theoretical purchasing power.
You better believe that will impact home prices, other things being equal. The good news is that the number of people this effects is relatively small and a 10% price drop would largely offset it. As mortgage rates rise, however, the GDS limit becomes more constraining.
14. Long-am Options:
Mortgage-Amortization-ComparisonAfter July 9, there will still be some lenders offering 30-year amortizations to people with 20% equity. But not the major banks.
If history is a guide, banks will enforce 25-year amortizations on all mortgages. Some might even do it before July 9.
15. Bundles:
According to OSFI, lenders will no longer be able to offer “a combination of a mortgage and other lending products (secured by the same property) in any form that facilitates circumvention of the maximum LTV ratio limit…”
bundle-mortgageThere is question on how this will impact “bundle mortgages.” A bundle refers to an 80% LTV non-prime mortgage with another lender’s 5% second mortgage behind it. This lets non-prime lenders offer 85% LTV lending solutions.
Bundles exist partly to avoid mortgage insurance. Federally-regulated lenders must insure mortgages over 80% LTV by law. If another lender holds the 5% second, it's a way around that limitation. (Borrowers can also arrange 5% seconds on their own if they like.)
As a side note, and slightly unrelated: This 80% uninsured LTV limit is rumoured to be one reason why TD shut down TDFS. The speculation was that OSFI didn’t like the fact TDFS was offering 85-90% LTV uninsured mortgages—albeit through a structure that was technically onside of the regs.
The OSFI spokesperson we asked wasn't able to offer clarity on the bundle question, other than to say, “The language in the guideline is clear.”
We can tell you, however, that many in the industry are anything but clear on it. 
If one interprets OSFI’s rule as preventing lenders from promoting bundles (as we’ve defined them), that would seem unreasonable. The risk to the regulated first mortgage lender is negligible because the highest risk money (the extra 5% LTV) comes from a totally separate, private and uninsured lender with segregated capital. Moreover, the first mortgage lender underwrites its risk as if it were lending at 85% LTV or above anyway.
16. Million-Dollar Babies:
…are going down with the bathwater. People buying $1 million-plus properties will soon have to plunk down 20%. Otherwise, they’ll no longer qualify for high-ratio insurance.
iStock_000013379755XSmallThat said, the Department of Finance tells CMT: “…$1 million properties with a down payment of at least 20% would still be eligible for (low-ratio) mortgage insurance offered by CMHC and private mortgage insurers.”
Flaherty says that wealthy people’s access to mortgage insurance is “not my concern…If someone can afford to pay a million dollars…they don’t really need CMHC. That’s not what CMHC is there for.”
If that’s true, Jim should probably update CMHC’s mandate. Last time we looked, its mandate was: “to allow as many Canadians as possible to access home-ownership on their own” and “in all parts of the country.” Vancouver and Toronto happen to be parts of the country, and they've got more $1+ million homes than homes under $300,000.
From a nationwide standpoint, high-ratio million-dollar mortgages are a small fraction of the pie. In Toronto and Vancouver, however, million-dollar home sales are 6-18% of the market respectively. 53% of single-family homes in Vancouver-proper are over a mil. (for now anyway).
By all accounts, a cut-off at $1 million is purely arbitrary. A million-dollar mortgage buys a lot less than it used to. Granted, it implies you’re better off than most, but it doesn’t make you “rich,” especially if you have to live in a major city.
There’s no public data on insured million-dollar mortgages, but CMHC tells us: “Of our total insurance-in-force distribution, five per cent of our mortgage portfolio had a loan amount exceeding $550,000 at origination. This includes high-ratio, low-ratio and multi-unit.” As a pure guess, high-ratio million-dollar mortgages are probably near or less than one per cent of CMHC’s overall portfolio.
Of course, even a fraction of one per cent of Canada’s 9.85 million homeowner households is tens of thousands of homes. If this news spooks a portion of those owners into selling more urgently, or concerned buyers defer buying, or buyers who need high-ratio insurance can’t get it, some high-end markets will suffer.
It’s worth noting that many million-dollar borrowers have sufficient net worth to make a 20 per cent down payment. They simply prefer to leverage their capital in other ways. Where that buyer has assets, impeccable credit and strong employment, those are very profitable low-risk insurance premiums for the government—premiums the government will no longer collect.
At day's end, assuming strong underwriting and conservative appraisals, the justification for this change is questionable. Alternatives could have been:  (a) setting the $1M threshold higher, (b) raising premiums on $1M+ properties, or (c) scaling back insured loan-to-values over $1 million.
17. Appraisals:
appraisalOSFI says, “In general, FRFIs should conduct an on-site inspection on the underlying property…” Lenders can still use automated appraisals, but OSFI expects them to use live appraisers if an application is deemed higher risk.
It will be interesting to see if more high-LTV mortgages are appraised. Currently, lenders and default insurers rely on auto-valuation systems on most of these applications.
18. Renewals:
mortgage-renewalIf you have a high-ratio insured mortgage with an amortization over 25 years, you shouldn’t have a problem renewing with your existing lender.
You’ll also still be able to switch lenders and keep an existing amortization over 25 years, assuming:
  • You don’t increase your loan amount.
  • Your loan-to-value doesn’t increase (which could happen if home prices dive), and
  • You have a regular mortgage (i.e., it’s not acollateral charge mortgage).
Of course, if you need to increase your mortgage in the future and have less than 20 per cent equity, you’d be limited to a 25-year amortization. People should keep that in mind if they’re buying with a 30-year amortization today and thinking of upgrading their property down the road.
19. Changes for Self-employed:
Self-Employed-Mortgages-WomenBanks who still have flexiblebusiness-for-self (BFS) underwriting policies today (there aren’t many left), probably won’t for long. OSFI has put more pressure on lenders to obtain “reasonable…income verification” from self-employed borrowers, such as an NOA and business formation documentation. Banks have been checking those docs very closely for income reasonability.
Mainstream lenders may stiffen BFS qualifications in other ways as well. As a result, many self-employed borrowers who tax-manage their earnings (i.e., don’t pay themselves enough salaries or dividends) will find mainstream stated income programs ineffective. That’ll force some otherwise-qualified borrowers into the arms of alternative lenders with much higher interest rates.
Some critics might ask, "Why should the government take risk for self-employed borrowers?" To that, one could argue, why should the government take risk for any mortgage borrower?
The answer is beyond the scope of this article (which is long enough already), but in a nutshell: There are substantial economic and social benefits to making home ownership accessible to low-default-risk borrowers who contribute to job growth and pay aprofitable insurance premium to the taxpayers of this country. Default risk is not linked to one-factor (income). It's determined by a borrower's total credit profile (assets, debts, cashflow, income stability, equity, beacon score, and so on).
20. Interest Savings:
interest-savingsThe DoF’s press release heralded the “$150,000” that “typical” families could save in interest, thanks to it winding amortizations back to 25 years. That’s great, but this is no consolation for qualified borrowers who are forced to allocate cash flow towards a mortgage instead of better uses.
The fact that shorter amortizations save interest is simple mathematics. But that doesn't make a 25-year amz the optimal strategy (or lower risk) for all.
Many qualified borrowers are better off with a long amortization and lower payments. They can then budget that money towards a higher-returning use, which might include education, retirement investing, a small business or a contingency fund.
Flaherty says that "most Canadians” borrow responsibly. Unfortunately, those responsible people will be restricted by these rules nonetheless.
Ottawa could have made borrowers qualify at a 25-year amortization, and leave the option of 30-year amortizations for payment flexibility. Like it sometimes does, however, the government took an easy shotgun approach to regulation with few provisions for exception cases. But it wasn't really about that. The real aim behind the amortization change was to slow the market, plain and simple. Policymakers probably barely considered the micro-economic repercussions for individual borrowers.
*******
Despite the short-term pain and any critical comments above, it is clear that housing volatility will be reduced by these moves, over the long term. And that’s a positive...if you look far enough out.
The questions are, how long is long-term, how unpleasant are the side effects, and could those side effects have be minimized by a more incremental implementation?
Whatever the case, credit is due to the DoF, OSFI and Bank of Canada on two fronts:  #1) They want to do the right thing, and #2) they are by no means intellectually challenged. All three consulted with some of the top minds in the country before making these decisions.
Their analysis has led them to conclude that deflating the housing market is appropriate at this uncertain juncture. Hopefully, their decision to substitute mortgage regulations for monetary policy works out. As Flaherty told reporters Thursday, it all comes down to a “judgment call.”


==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Friday, June 22, 2012

Misplaced anger?


Back on March 22nd, Vancouver Sun columnist wrote a column that garnered a lot of attention in the real estate blogosphere.

Ostensibly the article was an attack on affordable housing.  A view reinforced by the headline which blared: "Affordable housing in Vancouver? Who wants that?"

It made me chuckle.

If you talk to those scribes who write for the mainstream news and have a conversation with them about their profession, there is one interesting complaint.

They don't get to write the headline for their columns.

It's their Editors who do that.  And often the writers themselves disagree with the choice of 'eye-catching' headline.

This particular column about the Vancouver housing scene was a rant against Social Engineering.

McMartin's opinion is that the meddling of the Social Engineer's rarely works and more often causes more problems than it solves.

In the case of housing affordability, he offered this quote:
"There's nothing that this task force can do to make Vancouver as inexpensive as Toronto or Edmonton. But I do believe it will mean changes in the processing of building permits, and in the wording of zoning bylaws that ultimately will lead to increased competition and more affordable housing choices."
To which McMartin countered that this would lead to more densification - an outcome he did not believe people wanted.

McMartin closed with another quote:
"The only thing that's going to make housing in Vancouver cheaper is a collapse in housing prices."

To which he replied:
Hands up, you well-meaning social engineers, who want that.

Now the real estate bear community jumped all over McMartin for this.

I think he got a bad rap, personally.

He was railing against social engineering.  The point he was making is that all the social engineers would create was more densification... not affordable housing, something most of us don't want.

McMartin was saying that the only thing that would create affordable housing was a collapse in housing prices. A fact, he noted, that none of the social engineers would actually want (if only due to the havoc this would create on social services).

And I agree with the point of the March article.

But because McMartin had spoke about his own travails with home ownership when he first moved to Vancouver, he was vilified for appearing to be against deflating the housing bubble.

Today McMartin came out with another article.

It concludes by noting:
"In the meantime, in the very near future, on Monday, Mayor Gregor Robertson’s Task Force on Affordable Housing will deliver its recommendations. After months of consideration and research, city hall will finally reveal how government can make housing more affordable, despite the fact that the market has been busily doing just that. In real estate, timing is everything."

It's another cheap shot at Social Engineering.

Those who want regulations on flipping houses, or regulations on foreign buyers, etc... they are missing the point.

Our real estate bubble has been created by cheap credit and policies that accommodated massive debt.

Flippers, speculators and foreigners may have capitalized on it... but they are not the problem to be addressed.

With this latest article, McMartin will get flack from the real estate blogging community again.

The headline, "The Market is Teetering! Happy Now? implies McMartin is unhappy with the regulatory changes that have just been made instead conveying what his column is actually doing: taking a shot at the social engineers.

McMartin isn't criticizing the steps just taken by Flaherty and Carney, he's taking yet another cheap shot against the Social Engineers.

And I completely agree with him.

Hopefully most of the blogging community appreciates what he is railing against.

Side note

Some interesting stats in the body of this latest article.

Meanwhile, Metro’s real estate market is holding its breath. Or possibly it’s stopped breathing. It’s hard to tell.

Sales in May for all forms of housing across the Multiple Listing Service were down over 15.5% from last year, and the lowest for the month of May since 2001.

The news for detached homes sales was even worse: They were down 25% for the same period last year.(Commenting on these numbers, the resolutely sunny Real Estate Board of Greater Vancouver decided this was “indicative of balanced market conditions.” But then the board would have viewed the crash of the Hindenburg as the result of “normal deflationary conditions.”)

While sales have fallen, the number of listings has risen. In the Vancouver westside, which is held up as the main beachhead for the Asian invasion, the total of active listings — those homes for sale that haven’t sold — has risen to 1,100 properties at present from 600 a year ago. That is, during all the time the alarmists were certain that Asian buyers were pushing up house prices across Metro, the market in that neighbourhood most cited as the cause of those rising prices was already languishing.

The take-a-way here is that the dreadful statistics are now getting mainstream coverage.

Combine this with the press from the latest Flaherty, Carney and OFSI offerings and the psychology of the general public regarding real estate is taking an absolute beating.

It will be fascinating to watch the last half of this year.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Thursday, June 21, 2012

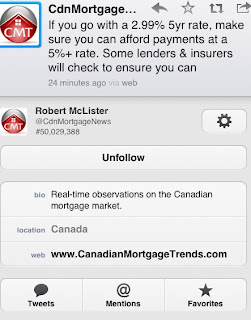
Thurs Post #2: A tweet to ponder


A interesting tweet this afternoon from Canadian Mortgage Trends...
"If you go with a 2.99% 5yr rate, make sure you can afford payments at a 5%+ rate. Some lenders and insurers will check to ensure you can."

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Thurs Post #1: Interesting Times


The third week of June, 2012 is rapidly turning into 'the week that was'.

Will we look back at this as a major turning point in our housing bubble?

It started off with the Vancouver Sun outlining upcoming changes for CMHC mortgages by the OSFI. A barrage of negativity hits the mainstream media telling people to prepare for changes like:
  • Home Equity Line of Credit mortgages reduced from 80% financing to 65% financing.
  • Lines of credit to be either amortized, or amortized after a specified period of time.
  • More stringent income requirements for self-employed borrowers.
  • All mortgages to be reviewed upon renewal (currently as long as payments are made, it is unlikely for a bank not to offer a renewal to a client).
  • Funds from cashback mortgages are not allowed as a source of down payment
  • Use of the five-year posted “benchmark” to qualify uninsured terms of one to four years and all variable terms (currently most lenders use a three-year posted or a lower rate to qualify uninsured mortgage).
  • More limits on underwriting exceptions.
  • Home insurance to be included in debt-servicing ratios (it is currently not included.)
  • More public disclosure of statistics pertaining to institutions’ mortgage practices.
  • More accountability from management to ensure lenders are adhering to their underwriting guidelines.
Egads.

These measures being discussed in the media are, by themselves, enough to create a stir. But that was just primer for the next round.

Canadian Mortgage Trends fired off a tweet earlier today which proclaimed: "What the industry didn't want to happen, happened"


And what are they referring to? What is the dire news they didn't want to happen?

CMT announced that the former No. 1 lender in the mortgage broker market announced that they are closing their doors to new business as of July 31, 2012.

FirstLine, a broker lending subsidiary division of CIBC, was put up for sale earlier this year but a deal could not be closed.

A source familiar with the discussions told CMT: “The buyer struggled to come to a deal that made sense so CIBC chose to let FirstLine die a natural death on its own."

This was a development CMT says marks "a moment of truth for the broker market."

But if that weren't enough, press reports last night confirmed what we alluded to yesterday. Specifically Ottawa is tightening up on mortgage rules.
"The country’s biggest banks were caught off guard on Wednesday night as the Department of Finance prepared to clamp down on mortgages by reducing the maximum amortization for a government-insured mortgage to 25 years from 30.

Ottawa will also limit the amount of equity that can be borrowed against a home to 80 per cent of the property’s value, down from 85 per cent.

Ottawa will announce two other changes, according to a source. It will no longer allow high-ratio mortgages over $1-million, and it will cap the gross debt service (which looks at a consumer’s total debt payments as a percentage of their income) at 39 per cent.”
The third week of June 2012.

I suspect we will be looking back on this as a significant signpost on the road that was the Canadian Housing Bubble.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.
Wednesday, June 20, 2012

Wed Post #2: Is the 30 Year Mortgage about to get axed?


Speculation is racing around the real estate community that Federal Finance Minister Jim Flaherty is about the axe the 30 year mortgage in Canada.

About an hour ago (at 5:19 PDT), Reuters made the following announcement:
Flaherty news conference at 8:15 a.m. (1215 GMT)

* Canada economy strong but faces big risks

(Reuters) - Canadian Finance Minister Jim Flaherty will make an announcement on Thursday at 8:15 a.m. (1215 GMT), the Department of Finance said on Wednesday evening without providing any details.

Flaherty will hold a news conference in Ottawa at that time, according to the brief statement.

Officials at the Finance Ministry did not immediately reply to requests for additional information and officials at Prime Minister Stephen Harper's office declined to comment.

Flaherty, who has been finance minister since 2006, faces a raft of domestic and international challenges to an economy that remained relatively healthy through the global financial crisis, including a strong housing market that some economists now fear is overheating.

He has just returned from Mexico where he accompanied Harper at a summit of the Group of 20 industrialized and developing nations, which focused on the European debt crisis.
A number of blogging sites are now speculating that Flaherty will end the 30 year amortization, bringing conditions full circle.

It was the increasing of the amortization from 25 years up to 30, then 35, then 40 years which many argue ignited the housing bubble.

We will see tomorrow.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Wed Post #1: China's Property Values continue to decline


Perhaps one of the most important stories for our little hamlet on the wet coast is the fact that China's property values continue to decline.

The chart above from ISI Research shows that the rate of decline is now similar to the lows in early 2009. And, as Pragmatic Capitalism notes, data from ISI tends to be more accurate than the official numbers coming out of China’s housing ministry.

As we have noted in earlier posts, much of this decline has been engineered by Beijing as China attempts to arrest their housing bubble.

And as Reuters notes, this policy will not be letting up soon. As an unnamed spokesman from the housing ministry was quoted as saying that “all localities must firmly implement various property tightening measures as required by the central government.”

Beijing is sending a stern message to local authorities to keep the measures place.

But, as China undergoes an economic slowdown, which may end up being more severe than the authorities had anticipated, will the tightening measures in the housing market be relaxed (particularly at the local level)?

Reuters notes that even if measures are relaxed, any rebound may be a ways off.

Vanke, China’s largest developer by sales, said earlier this month it would take about 11 months to sell down unsold stocks in key cities such as Beijing, Shanghai and Shenzhen should the market rebound.

Hui Jianqiang, head of research at the China Real Estate Association, told Reuters that he doesn't see a rebounding market.
“I’m not worried about a home price rebound as long as the government keeps its tightening stance.”
Presumably we shouldn't look to see a HAM rebound here in the foreseeable future either.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Tuesday, June 19, 2012

A.P.B.?


One of the realities that your faithful scribe has to deal with sometimes is that life gets in the way.

Now don't get me wrong.  I didn't just fall off the earth and it's not like all heck broke loose.  I had several nice blog entries planned out so that I didn't have to be around the computer.  I set them up in Blogger to be posted automatically on Friday night, Saturday and Sunday.  

But I formatted the date incorrectly. Ooops.

So that explains the weekend.  

As for yesterday and today... I just plain got busy. I hope you will forgive me. I appreciate the concerned posts and emails wondering if I was alright.

I am.

So cancel the All Points Bulletin, and the planned milk carton campaign... I haven't gone missing. 

Back to posting tomorrow.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Friday, June 15, 2012

Friday Post #1: The message is out there


Increasingly, as the mainstream media repeats the message, the reality of the real estate market is seeping into the public consciousness.

The latest missive comes courtesy of the North Shore News which blares: West Van home buying frenzy loses steam.
Recently released reports on the Lower Mainland’s real estate market hold a message for the sellers of high-end homes in West Vancouver: The party, it would seem, is over.

In a June 4 data package, the Real Estate Board of Greater Vancouver reported that regional home sales had seen their slowest May since 2001, and that the decline had been led by a once white-hot West Vancouver and other pricey enclaves.

For much of last year and perhaps longer, the Lower Mainland saw a frenzy of buying at the upper end of the market, widely believed to be driven by an influx of investment from China. The phenomenon pushed the price of already expensive property into the stratosphere, with a typical West Vancouver detached home jumping 20 per cent in just 12 months, according to the board. Tony neighbourhoods in Richmond and Vancouver’s west side saw similarly disproportionate booms.

The latest batch of data, however, suggests that surge in luxury purchases has slowed. Sales in West Vancouver saw a dramatic drop in May, according to the real estate board, with just 100 residences changing hands compared to 201 for the same month last year.
The North Shore News notes that despite the apparent slowdown at the high end, home prices in West Vancouver haven’t dropped significantly - yet.

But the News also notes that "other reports released this week suggested the outlook for the whole Lower Mainland market will soon darken."

Much like the locally produced X-Files mantra, the truth is out there.

And if conditions don't change by autumn, the term 'fall' could be used to describe much more than the season.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Wednesday, June 13, 2012

Home Grown Housing Porn


It's only fitting that since we have North America's largest housing bubble that the housing porn TV shows should gravitate to our 'hood.

Corus Entertainment’s W Network announced today that the west coast spin-off of W Network’s hit house pimping series Love It or List It has been given the go-ahead and is scheduled to launch in winter 2013.

Interior designer and TV personality, Jillian Harris (The Bachelorette Season V, Extreme Makeover: Home Edition) will co-host Love It or List It Vancouver.

Harris’ co-host will be announced at a later date.

Produced by Big Coat Productions in association with W Network, Love It or List It is a long standing flagship series show for W Network.

Vibika Bianchi, Vice President, Original Programming, Lifestyle, Reality, Factual Entertainment, Corus Entertainment said,
"With Season 5 now well underway, the time is right to bring the winning formula to Vancouver’s hot real estate market."
According to the press release, Love It or List It Vancouver will showcase families
"... in B.C.’s largest metropolitan city who are struggling with homes that no longer suit their needs. It’s up to Jillian to put a stop to the wandering eyes of our homeowners, armed with a list of 'must-haves' and a design she hopes will persuade them to stay. Meanwhile, the realtor is determined to get homeowners to relocate by taking the homeowners list of “must-haves” and finding them new digs.

Set in one of Canada’s largest real estate markets, the beautiful Pacific west coast, every episode will take viewers on an emotional rollercoaster as Jillian and her soon–to-be announced co-host implement their plans to battle it out for the homeowners’ allegiance. With renovation there are always setbacks and sometimes it means the homeowners must lose one of their “must- haves” on their list to stay. On the realtor’s end, finding everything the homeowners want in their dream home can be more difficult than originally anticipated. The stakes are high as the homeowners weigh in on the financial and emotional decisions of buying a new home or staying in the renovated one."
You can only marvel at the unfolding scenario here.

Winter 2013 is over half a year away.  

Vancouver's real estate sales are plunging, listings are exploding.

One wonders if, by air time, the show could morph into "Love to list it, Desperate to sell it"

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Tuesday, June 12, 2012

Seattle Soaring?


When talk turns to real estate in the United States, the general trend is one of ongoing despair.

The Case-Shiller index continues to tell a dreary tale and gloom and doom is abounds.

Which is why we raised an eyebrow at this headline from the Seattle Post Intelligencer: "Seattle Real Estate Roaring." (hat tip DM)

The PI reports that real estate sales in Seattle are the most dramatic in at least five years.

In fact home sales have been on the rise for months, but the PI says previous gains in homes prices had been minor.

May’s real estate statistics, however, have solidified the up trend and pushed it into overdrive.

Prices of houses sold in Seattle increased 10.5 percent year-over-year. The lacking inventory of Seattle homes for sale in the most popular neighborhoods has created bidding wars and sellers are becoming more confident in pricing their homes higher in recent months. Condo prices gained 7.4 percent, with the same dearth of inventory creating a serious shortage as buyers struggle find available condos in South Lake Union, Downtown, and Capitol Hill.

Total sales of houses in Seattle climbed 22.3 percent in May, as compared to the same month in 2011. Sales of condos increased 29.6 percent, a whopping increase of nearly 1/3 more sales, while at the same time inventory of available Seattle real estate was down 37 percent.

The picture is similar on the Eastside with slightly muted numbers, as we’re seeing 1-2 percent gains in home prices, but a 19 percent increase in the number of total Eastside home sales. Based on Seattle’s trend, the Eastside may follow suit shortly and be in for a significant bump.

Overall, King County house prices saw a gain of around 5 percent and condo prices saw a drop of about 2 percent, with Seattle’s large gains offsetting some price drops in outlying areas of the county. Total sales in King County increased 24 percent for houses, and 25 percent for condos.

The PI says Seattle housing inventory numbers very low right now. And while there will certainly be more short sales and foreclosures coming to the market in the future, the PI believes the current market for traditional resale and new construction home is strong and hasn’t looked this good since 2006.

Which the paper notes feels like a lifetime ago.

Is it an anomaly... or is the market turning around for the Emerald City?

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Monday, June 11, 2012

Mon Post #2: Real Estate Forecast - Part 2


Did you catch the recent real estate forecast by TD Bank?


You will recall back on June 1st, we posted the May 2012 detached average home price in Vancouver.  May's total was $1,037,331, down from February’s high of $1,235,244. It means the average single family home price has now dropped 12% Year Over Year (YOY).

Some concluded that this means we are a mere 3% away from the TD prediction of a 15% drop.

But is that what TD said?

TD Economists Derek Burleton and Leslie Preston said that they expect:
"house prices in Toronto and Vancouver to sink by at least 15% over the next two to three years."
They are saying prices could sink 15% over the next 2-3 years. That suggests its in ADDITION to the 12% drop we have already experienced.

That would take the Vancouver slide to almost 30%.

More significantly:
"Mr. Burleton and Ms. Preston expect a price decline of that size over the next two to three years... having said that, a "severe shock" from overseas could speed that up."
Oh?

Is TD telling us we could see a 30% collapse in Vancouver housing prices within the next year?

Seems to be a pretty stunning forecast to me.

Wasn't it just the other day we were discussing how some thought a 30% drop was unimaginable?

It seems TD doesn't have a problem conjuring that vision.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Mon Post #1: Real Estate Forecast - updated


Excellent interview with David Lepoidevin of National Bank on BNN about real estate last week (hat tip to Fish from Fishyre).

If you missed it you can watch it here.

Transcript excerpts courtesy of VREAA:
"Where we are concerned is regarding the value of Canadian real estate. The lessons from the world have been that real estate has had greater implications than just the value of your investment properties.”

“In Canada if you look at the actual numbers, the numbers don’t lie. If you look at median real estate prices compared with those in the US, at their peak the median US housing price was $265,000. Today in Canada, the latest figures we have is $375,000 for the median real estate price transaction. So therefore we are 42% higher in Canada today that the US was at the peak. And we’re [about twice] the median price in the US today.”

“Many of the banks are more exposed [to the mortgage market] than they have ever been. CIBC has 50% of their loans in real estate. When we got into trouble in the early 1990’s, the average Canadian bank was about 13% exposed to RE, and we know we got into a heap of trouble then [with overexposed institutions].”

“The Canadian bubble has extended far beyond the US bubble. We’re beginning to see cracks in the system and the cracks are coming from my home town which is Vancouver, which may have been the epicenter of the bubble. A stand-alone house in Vancouver was over $1 million and still is over $1 million.

Reports are coming in that Asian money is slowing to a trickle. [Real estate prices in China are dropping.] The frenzy had spilled over into Vancouver almost as a suburb of China. [The money has stopped because the Chinese real estate market has slowed but also because the investor immigrant program has ‘shutdown’.”

“If we look at the percentage of jobs in actual construction (this isn’t realtors this is actually guys swinging hammers) ... we can see that Canada, the red line, is way above not only where the US is today, but we are significantly higher at 7.5% compared with 5.5% in the US at their peak.”

“So we need to define whether there is a bubble and what I’m trying to point out to people is, yes, there is a bubble.”

“The myth in Canada is that real estate cannot go down unless there is a spike in interest rates. In the United States interest rates of 2% lower than they were when housing prices will almost double what they are today. So it wasn’t a spike in rates that caused house prices to go down it was a reduction in the availability of credit, tightening credit. We now have the first Canadian majority government we’ve had in 8 years and they are beginning to put the brakes on.”

“If we did an Internet search for ‘boom and bust’ you will find hundreds of examples in history, in various economies, of boom bust cycles. If you do an Internet search for ‘boom’ and ‘soft landing’ there are no entries. There are none. ‘Soft landing’ are the scariest words in investment history because they don’t happen. We are trying to engineer a soft landing in real estate just as the Chinese are. The NASDAQ bubble, the US housing bubble,The Canadian housing bubble... You will not find a soft landing.”

==================
Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Sunday, June 10, 2012

Conflict of Interest?


If you follow Real Estate in the Village on the Edge of the Rainforest, you are well acquainted with C. Tsuriel (Tsur) Somerville.

Somerville's official title is Associate Professor, Real Estate Foundation Professorship in Real Estate Finance Director, UBC Centre for Urban Economics and Real Estate.

(try saying that 3 times fast)

The Vancouver bear blogosphere prefers to call him "that real estate flunky from the UBC Sauder School of Business."

He earns that title because, as the media's 'go-to' guy when a 'non-partisan' expert opinion is sought, he seems to constantly come across as nothing more than a spokesperson for the Real Estate industry.

Take, for example, this quote from an article in the Globe and Mail last month.

As sales slump and listings soar, the Globe comes out with a story headlining "Cooler housing market no catastrophe."
To hear some people talk, one of the hottest housing markets in the world is experiencing a serious course correction. Prices are down significantly over last year. But what does that mean?

Tsur Somerville, the oft-quoted real-estate economist from the University of B.C., doesn’t see signs of a major real-estate story brewing. He actually holds a refreshing perspective on the local scene. He won’t even go so far as to say that buyers hold the advantage at the moment, even though supply far exceeds demand.
Critics content Somerville will NEVER go so far to say that it's a buyer's market, a viewpoint driven largely by comments like this one from a recent Vancouver Sun article titled 'Vancouver's Housing Market unlikely to face significant price correction - expert':
Although the Vancouver housing market may be out of equilibrium, a significant correction is not expected, said Tsur Somerville, director at the University of B.C. Centre for Urban Economics and Real Estate at the Sauder School of Business.
To those who watch Real Estate, Somerville is as R/E optimistic as every single rah-rah realtor who eternally flogs the 'it's a great time to buy' mantra.

So is all the criticism of Somerville simply sour grapes from the real estate bear blogosphere because the man, an expert in his field, won't come out supporting the outcome they foresee?

Or does Somerville actually have a bias toward supporting the real estate industry?

Last week a faithful reader passed on this interesting link to me (hat tip alexcanuck).

It's the website for the Sauder School of Business. Specifically the sponsorship page acknowledging those companies who provide significant funding to the Centre for Urban Economics and Real Estate.

i.e. The source of funding for Tsur Somerville's paycheque.


Toss into the mix the fact that the courses he teaches at the Sauder School of Business are:

  • Commerce 307 - Real Estate Investment
  • Commerce 408 - Real Estate Development

And you would be hard pressed to believe that someone who teaches you about investing in real estate or developing real estate - two field's where boundless optimism is crucial - then it's doubtful this person is going to come out and tell you the market is in trouble.

Besides... if he's telling you the market is in serious trouble, who's going to sign up to take his courses?

So what do you think?

Is there a conflict of interest... or at least the perception of a conflict of interest here?

I suspect in a poll of the bear blogopshere, the answer is all too obvious.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Saturday, June 9, 2012

Have I got a deal for you!


You know our housing bubble is big when the get-rich quick crowd set up shop.

Not even Ron Popeil nor the Slap Chop dude were this shameless.

Ever heard of Lucrii Investments?

No?... I hadn't either until a faithful reader pointed me to them.

And your gonna love this one (click on image to enlarge).


Lucrii Investments appears to be a 'wanna-be'  real estate investment club.

On their homepage, they offer you the chance to get in on the real estate gravy train even if don't have the cash to get in.
"How do you buy a million dollar home with none of yours or the bank's money, or obtain more properties when you have reached your limit to borrow?"
(I dunno? Scam others out of their cash? But I digress...)

Lucrii tells you you can do this by using "Creative Techniques":
How do you buy a million dollar home with none of yours or the banks money?

One can obtain between 60-80% cash value on a property from a hard money lender. This said the hard money lender will take an agreement with the property as insurance for their repayment of the funds. Because they only lend 60-80% of the FMV of the property this requires a deal where one obtains the property for 20% below FMV or more.

How can you obtain more properties when you have reached your limit to borrow?

There are other ways to obtain properties without borrowing. One type called a Vendor take back is just this. The owner or seller of the property agrees to hold the mortgage and take payments on their property with the ability to take the property back if payments are not kept. Now if your asking yourself why someone would do this, if they own the property out right and take the mortgage themselves they earn the interest rate not the bank.
Umm... okay.

Apparently their name,"Lucrii",comes from "Dei Lucrii", which are Roman gods of profit and wealth. Is that what these guys can offer you?
"Here at Lucrii investments we only deal with investments that yield the greatest profit, to do this we use a unique method to seek out only the most lucrative deals. This is the same system that has enabled top real estate investors such as Alan Casden, Donald Trump, and Theodore Lerner to be featured in forbs magazine. What this means for you is that you will be able to enter the 20%-50% below FMV arena, but what this really means is that you will be able to confidently take control of your profits there for taking you and your family to the next level."
Umm...? Did they really just call it "forbs" magazine?  Yup...


Okay... small typo.  Doesn't mean they're a bunch of amateurs, right?

I mean they tell you right here that they have almost a decade of negotiation and sales skills...


Plus... they bring you "only deals that are significantly below market value. This spells out profit wether  on a flip or purchasing to buy and hold."

(Umm... did they just misspell 'whether' too?)

So what is this unique method they use to "seek out only the most lucrative real estate deals?". What is this system that propelled Alan Casden, Donald Trump and Theodore Lerner to fame in Forbes (forbs) Magazine?


Seriously?

The contact numbers on the flyer and on the website are the same:
Scott L
Email: ScottL@lucriiinvestments.com
Phone: 604-230-7825

Tyler J
Email: TylerJ@lucriiinvestments.com
Phone: 604-562-2148
I wonder what Google can tell us about these phone numbers.


Google is littered with results relating to the rave and DJ scene, specifically concert promotion.

In fact I'm willing to bet there's just over four years of results for Tyler and Scott ("almost 10 years experience.")

It's said that at the end of all speculative bubbles you have everyone and anybody piling in to get a piece of the action.

Clearly when it comes to our real estate bubble... we're there.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Friday, June 8, 2012

Ain't Gonna Happen??? Hmm... perhaps it should be - How Low will it Go?


Our housing bubble is now mainstream news.

Sales of existing homes in Vancouver sank 15.5% from a year ago May, with the sales for the month coming in the lowest for any May since 2001.

At the same time the active inventory backlog surged 16.8% and new listings were up 14.4% from a year ago.

As listings soar and sales tank, the man on the street in now openly discussing 'The Bubble'.

But talk is now moving past whether or not there is a bubble. Gluskin Sheff chief economist David Rosenberg is in the Financial Post proclaiming that Vancouver’s housing bubble has burst."

It all comes on the heels of May data which shows Vancouver's single family houses are now down 12% with no signs the slide is going to stop anytime soon.

Garth Turner takes a look at the data and proclaims:
"The event’s just begun. This was a lesson bitterly learned by those early vultures who swept down on US real estate in early 2006, smelling blood, only to end up catching a falling knife. After doubling in value over the last eight years, with the economy marking time, salaries trailing inflation and unaffordability off the chart this market is not going to clock out at fifteen per cent. If prices can dip 12% in a few months, they can decline 40% over the next 18 months."
True... but for many 40% is just too hard to fathom.

Consider this musing from Vancouver realtor Larry Yatkowsky.  He broaches the concept of a 32% drop in prices and consider's it a level most of us would not imagine:
Let’s start at the highest average price ever reached in Vancouver for a detached home – a mere $1,235,244. Now let’s also assume this market is on the skids sliding down the drain faster than we think to bottom out at something most of us would not imagine – a market that drops so much it hits May 2009′s Average Price of $831,171. With a price drop of $404,073... that's a 32% drop from the all time high.
Of course some of us can imagine it.  We don't think it's all that hard, actually.  But the disbelief in daily discourse is more than palpable.

Even in our little corner of the blogosphere it draws comments of incredulity.

On Tuesday we made a post about Random Thoughts.

Among the commentary that followed, one faithful reader (DG) opined:
"I would agree with prices dropping but your prediction is beyond impossible. It is basic economics and as you can see from the various RE blogs that there are people sitting on the sidelines waiting for the drop to enter into the market. There are many. These people will support the price and keep them from dropping beyond 20 to 30% as rates continue to stay low."
So a 30% drop is impossible?

My prediction, as you know all too well, is for a drop of 70-85% when all is said and done.

But I can't help but be fascinated by the steadfast belief by so many (... I say this because I encounter it in day-to-day discussions as well) that prices simply won't drop beyond 30%.

Even Yatkowsky finds a drop of 32% unimaginable for most.

Thus our post.

Ain't Gonna Happen vs. How low will it go?

So the first major signpost on this journey is the 30% mark. We will watch and focus on it.

Unimaginable? Unattainable?

With apologies to Rod Serling...
"This highway leads to the shadowy tip of reality: you're on a through route to the land of the different, the bizarre, the unexplainable... Go as far as you like on this road. Its limits are only those of mind itself.  That's the signpost up ahead - Next stop... The Bubble Bursting Zone."

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

Wednesday, June 6, 2012

The falling knife


On Monday we told you how Eugen Klein, president of the Real Estate Board of Greater Vancouver (REBGV), called May's negative real estate sales numbers a signal we were entering "a stabilizing period."

Most readers of this blog probably covered their mouths and coughed "horsesh*t" as they read that line.

Yesterday it was Tsur Sommerville's turn and his analysis was a little more bang on,

In the Vancouver Sun, Sommerville said he latest Metro Vancouver real estate numbers are "very clear signs" of a slowdown in the market.
"We're getting this consistently now. We're in a market that's much slower than what we're used to and I think that will transfer into much more sluggish prices, at best."
Much more sluggish prices, AT BEST, is right.

The negative feedback loop has now cycled into full gear and each day it seems the gloom and doom is making the mainstream news and permeating public consciousness.

Naturally the real estate industry will bend over backwards from portraying these conditions as anything near 'negative'.

Cameron Muir, chief economist for the B.C. Real Estate Association, maintained that the market remains balanced.
"Overall, the market remains in balanced territory, which means no particular advantage for either the buyer or seller. We won't see much upward or downward pressure on the pricing side."
Plunging sales combined with soaring listings... how could that influence prices?

Unfortunately for the spin meisters, the reality is reflected in quotes like that from realtor Larry Yatkowsky:
"On average, about a 150 or 160 homes in Vancouver are reducing their price every day in the hope of catching, getting ahead of the train and maybe get out before they can't."
Who would want to play catch in this market?

Who would council someone to play catch in this market?

All I can do is sigh and shake my head.

==================

Email: village_whisperer@live.ca
Click 'comments' below to contribute to this post.
Please read disclaimer at bottom of blog.

